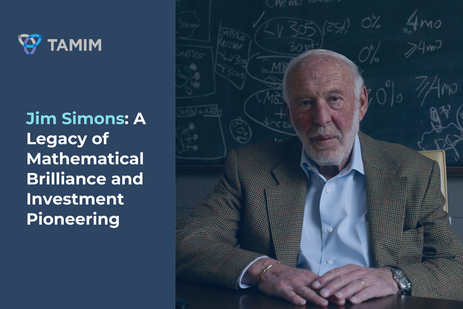
The investment world mourns the loss of another titan: Jim Simons, a prizewinning mathematician who transitioned from a stellar academic career to finance — a field he initially knew little about — to become one of Wall Street’s most successful investors.
Simons, who passed away at the age of 86, leaves behind a legacy marked by groundbreaking achievements in quantitative investing, significant contributions to mathematical research, and a remarkable commitment to philanthropy.
Simons’ journey into investing is nothing short of unconventional. A mathematical genius and former code-cracker for the US government, he initially dabbled in the stock market as a side interest. After leaving his code-cracking career, he started an investment fund, initially using a fundamental investment approach. When this strategy didn’t yield the desired results, Simons leveraged his mathematical expertise to develop quantitative methods for exploiting market inefficiencies. The results were extraordinary.
As we bid farewell to this visionary, it’s crucial to reflect on his life, achievements, and the invaluable lessons he leaves behind.
Early Life and Mathematical Legacy
Born in Massachusetts, on April 25, 1938, Simons’ early life was marked by a profound love for mathematics.
He pursued his passion for the subject with unwavering dedication, earning a bachelor’s degree in mathematics from the Massachusetts Institute of Technology (MIT) and a PhD in mathematics from the University of California, Berkeley. Following the completion of his PhD thesis, he collaborated with Shiing-Shen Chern and yielded the groundbreaking Chern-Simons theory, a mathematical framework with profound implications for fields ranging from geometry to quantum physics. Simons’ mathematical prowess earned him prestigious accolades, including the Oswald Veblen Prize in Geometry.
Simons’ career took a notable turn when he embarked on a career as a codebreaker for the U.S. Department of Defense during the Vietnam War.
It was during this time that Simons honed his skills in cryptanalysis and developed a deep appreciation for the power of computational analysis. However, Simons was drawn to the world of academia. From 1964 he taught mathematics at MIT before standing as chair of the mathematics department at Stony Brook University from 1968 to 1978. Simons made significant contributions to the field of geometry and theoretical physics.
Revolutionising Finance: A Quantum Leap in Investing
After publishing groundbreaking studies in mathematics that influenced quantum field theory, string theory, and condensed matter physics, Jim Simons decided to apply his genius to a more practical endeavour — generating substantial wealth quickly.
In 1978, at age 40, Simons took an unexpected turn and ventured into finance. Ten years later, he founded Renaissance Technologies, a quantitative hedge fund that would redefine the investment landscape. Rejecting traditional methods, Simons pioneered mathematical models and algorithms, assembling a team of brilliant mathematicians, physicists, and computer scientists. Together, they developed complex models to identify patterns and exploit market inefficiencies.
This quantitative approach, coupled with Simons’ unwavering commitment to rigorous data analysis, achieved extraordinary success with the flagship Medallion Fund. Renaissance Technologies’ Medallion Fund, open only to employees and their families, generated a compounded average growth rate (CAGR) of 66% over 33 years before fees, making it one of the most successful hedge funds in history.
Simons equipped his colleagues with advanced computers to process torrents of data filtered through mathematical models, transforming the firm into a virtual money-printing machine. This performance outpaced renowned investors like Warren Buffett and George Soros.
“No one in the investment world even comes close,” wrote Gregory Zuckerman, one of the few journalists to interview Simons and the author of his biography, “The Man Who Solved the Market.”
Philanthropic Legacy
Jim Simons’ impact on the financial world extends far beyond his investment prowess, evidenced by his profound philanthropic endeavours.
Alongside his wife Marilyn, he established the Simons Foundation in 1994, with a mission to support research in mathematics, science, and medicine. Their visionary initiatives, including the Simons Foundation Autism Research Initiative and Simons Collaborations, have catalysed groundbreaking discoveries and transformed scientific inquiry. Simons’ philanthropic vision also encompassed education, as evidenced by his founding of Math for America, a nonprofit organisation dedicated to supporting Science, technology, engineering, and mathematics (STEM) educators in New York City schools.
Through his unwavering commitment to empowering educators and advancing scientific research, Simons leaves behind a lasting legacy that will continue to shape the future of mathematics and science for generations to come.
Lessons Learned and Enduring Principles
Throughout his illustrious career, Jim Simons epitomised the principles of intellectual curiosity, perseverance, and innovation. From his early achievements in mathematics and code-breaking to founding Renaissance Technologies, Simons relentlessly pursued unconventional methods to achieve remarkable success in finance. His emphasis on rigorous research and quantitative models deviated from traditional investing approaches, showcasing his commitment to what he excelled at rather than conforming to established norms.
Simons faced personal tragedies, losing two sons, yet his resilience and dedication to his work and philanthropy remained steadfast. His legacy in both mathematics and finance serves as a powerful reminder of the transformative impact of intellect, innovation, and persistence. Jim Simons’ life and achievements will continue to inspire future generations of mathematicians, investors, and philanthropists, reminding us that true greatness lies in relentless pursuit and dedication.Vale Jim Simons.
Headlines in local financial news have recently featured stories of takeovers, mergers, and acquisitions. The beginning of this decade, marked by a significant downturn, has led to an economic cycle ripe with such activities. This bustling environment presents rich opportunities for unique non-blue-chip companies, especially those with smaller market caps.
In today’s market, both public companies and private equity firms are actively seeking to expand through strategic acquisitions. Competing businesses are eyeing specific assets to boost efficiency, while overseas entities, aided by favourable exchange rates, are acquiring at reduced costs. These acquisitions can enable companies to integrate new segments or enter new markets swiftly, bypassing the challenges of organic growth.
However, it’s important to remember that not all takeovers result in shareholder value. While some deals offer attractive premiums, others serve as a reminder of the risks and complexities inherent in M&A activities.
Adamantem Capital Wins Out in QANTM Bidding War
QANTM Intellectual Property Limited (ASX: QIP) announced last Thursday that it had agreed to enter a binding scheme of arrangement with Fox BidCo Pty Ltd, an entity owned and controlled by funds managed and advised by Adamantem Capital Management Pty Ltd.
Adamantem Capital winning the battle to acquire QANTM for $1.817 per QANTM share with the opportunity to elect to receive either 100% cash, or a 50% cash 50% scrip combination. This follows on from just days earlier having received an unsolicited non-binding indicative proposal from IPH Limited (ASX: IPH), a leading intellectual property group, expressing interest in acquiring all QANTM shares through a scheme of arrangement.
IPH’s proposal included offering 0.291 IPH shares and a fully franked special dividend of up to $0.11 cash per QANTM share, valuing the company at $1.90 per share. A premium to the accepted Adamantem Capital offer.
This takeover represents a significant premium for QANTM shareholders with the company trading hands for under $1 less than 6 months ago.
IPH announced their disappointment to the market in an update stating:
IPH is disappointed that it did not have an opportunity to engage with QANTM to pursue a combination of QANTM and IPH. IPH believes the combination has the potential to create material value for both QANTM and IPH shareholders by bringing together complementary member firms’ service offerings, greater diversification of clients, opportunities to accelerate growth in Asia Pacific through an enhanced combined platform and the unlocking of meaningful synergies.
QANTM’s bidding war ends despite IPH’s bid surpassing a previous offer from Adamantem Capital.
300 Million Reasons to Smile
Pacific Smiles Group Ltd (ASX: PSQ) has been subject to a drawn out takeover by Genesis Capital which took a turn at the end of last month.
The dental group which currently operates 120+ dental centres was subject to an initial bid from Genesis back in December 2023. The bid of $1.40 per share followed notification that it had taken up an 18.75% position in the Pacific Smiles. The attempted acquisition was quickly rebuffed by the board with the suggestion that it did not adequately reflect the strategic value of the Pacific Smiles business and appeared opportunistic in nature.
Genesis was not deterred.
While it took some time the private equity group returned with an increased offer of $1.75. It had also increased its position size in the company in January to 19.90%. This improved offer appeased the board which granted Genesis the opportunity to conduct further due diligence, on a nonexclusive basis, to enable it to put forward a binding proposal.
Enter National Dental Care (NDC).
At the end of April Pacific Smiles entered into a scheme of implementation with NDC to acquire 100% of the shares in Pacific Smiles for cash consideration of $1.90 cash per share, valuing the company at a touch over $300 million. Pacific Smiles will also have the discretion to pay shareholders a fully franked dividend of up to a maximum of 12 cents per share, with any dividend declared reducing the cash consideration of the $1.90 per share under the arrangement. The increased bid has received a unanimous recommendation by the board.
Will we see a return offer from Genesis? We wait with bated breath.
A Perpetual Nightmare
Not all takeovers end positively.
The recent narrative surrounding Perpetual, a stalwart in the funds management sector for 138 years, serves as a poignant reminder that not all takeovers culminate in success. A six month internal review culminated in a deal to sell its corporate trust and wealth businesses for $2.2 billion to Kohlberg Kravis Roberts & Co (KKR).
Perpetual’s ambitious foray into M&A with its acquisition of rival fund manager Pendal for $2.32 billion proved to be a pivotal misstep.
Despite hefty investments and strategic manoeuvring, investor sentiment remained tepid, and Perpetual’s share price languished, failing to recapture its former glory. The KKR bid follows the rejected bid from major shareholder Washington H. Soul Pattinson of $3 billion back in November 2023. The decline in offer serves as a timely reminder to shareholders that not all takeovers end in wealth creation.
The TAMIM Takeaway
Amidst an ever-evolving market characterised by sustained acquisition activity, the pivotal role of a capable and adept management team cannot be overstated.
While a number of examples of recent takeovers have indeed yielded value for shareholders, they also serve as a reminder of the inherent risks and complexities embedded within mergers and acquisitions. Despite the allure of premium valuations and envisioned synergies, the outcomes of such transactions may diverge from initial shareholder expectations. The cautionary tale of Perpetual vividly underscores the imperative of conducting comprehensive due diligence and exercising strategic foresight when navigating the intricate realm of corporate takeovers.
Prudence and discernment remain paramount in safeguarding shareholder interests amidst the allure of potential growth opportunities.
Disclosure: Pacific Smiles Group Ltd (ASX: PSQ) and QANTM Intellectual Property Limited (ASX: QIP) are held in TAMIM Portfolios as at date of article publication. Holdings can change substantially at any given time.
This week’s reading and viewing list Big Tech Capex and Earnings Quality, How Walt Disney Built His Greatest Creation: Disneyland and Berkshire Hathaway’s 2024 Q&A Session.
📚 Big Tech Capex and Earnings Quality (John Huber)
📚 Broken Record: An open letter to Western politicians on Russia. (Doomberg)
📚 There’s More to Warren Buffett’s Game Than Just Picking Great Stocks (Jason Zweig, WSJ)
Technology advancements, particularly in artificial intelligence (AI), have been pivotal in driving market dynamics recently, with notable companies like Nvidia (NASDAQ: NVDA), Meta (NASDAQ: META), and Alphabet (NASDAQ: GOOG) experiencing significant stock price surges of 210%, 102%, and 58% respectively over the past 12 months.
Amid this transformative era, the necessity for improved infrastructure becomes obvious, positioning specialty contractors like EMCOR Group Inc. (NYSE: EME) as essential. With an impressive 123% share price surge over the past year, EMCOR stands out for its strategic role in modernising and sustaining the frameworks critical to supporting these burgeoning technologies.
Company Overview
EMCOR makes high-tech manufacturing possible. The company operates through over 80 dynamic subsidiaries, boasting more than 35,000 skilled employees across 180 locations. The company’s operations are segmented into three primary divisions, each specialising in critical aspects of construction to serve a diverse range of corporate and public sector clients:
EMCOR Construction Services (ECS)
ECS provides innovative design-build services that meet fast-track schedules and unique engineering demands. ECS specialises in electrical construction, mechanical construction, and fire protection
The division is a nationwide group of mechanical and electrical contractors with experience in virtually all U.S. markets— commercial, healthcare, institutional, education, hospitality, manufacturing, transportation, and water and wastewater treatment.
EMCOR Building Services (EBS)
EBS ensures facilities across the U.S. operate at increased efficiency through a blend of self-performed and supplier-managed services. This division handles everything from HVAC maintenance and energy upgrades to comprehensive interior and exterior services, supporting a wide variety of facilities.
EMCOR Industrial Services (EIS)
EIS provides comprehensive maintenance, construction, engineering, manufacturing, and fabrication services across North America. From an investment standpoint, EIS’s approach to providing integrated solutions through a single-source provider delivers significant value to major industries. This division’s ability to offer bespoke contracting strategies is particularly advantageous, allowing EMCOR to meet diverse client needs with precision and effectively manage complex projects, which can enhance profitability.
Strategic Positioning and Growth Opportunities
EMCOR’s strategic positioning within the infrastructure sector is significantly enhanced by legislative tailwinds provided by the Infrastructure Investment and Jobs Act (IIJA) and the Inflation Reduction Act (IRA). These acts represent a monumental federal investment totaling US$1.25 trillion, earmarked for revitalising and expanding the U.S.’s transportation, energy, water resources, and electrical infrastructures. EMCOR is poised to benefit from these initiatives, as the company’s extensive capabilities in mechanical and electrical construction align directly with the U.S’s renewed focus on infrastructure improvement.
Additionally, EMCOR’s expertise in high-tech sectors such as data centers and semiconductor manufacturing positions it at the forefront of industries increasingly driven by AI technologies. These projects demand sophisticated electrical and mechanical constructions—areas where EMCOR excels.
Additionally, the increased focus on indoor air quality maintenance, driven by concerns over wildfires and public health issues like the COVID-19 pandemic, places EMCOR in a prime position to capture new revenue streams in this essential service area. As these sectors evolve, EMCOR’s diverse capabilities and extensive reach enable it to effectively leverage macro growth trends.
By aligning its operations with significant federal investments and the frontiers of technological integration, EMCOR is not just participating in the hot trend of AI and digitisation; it is actively shaping the future of industrial and energy infrastructure, ensuring relevance for the coming decade.
The Infrastructure Decade
Dubbed the ‘Infrastructure Decade’ by the Biden administration, this period is defined by significant legislative acts and fiscal stimulus like the CHIPS act, IIJA and the IRA. Despite a divided Congress, the groundwork laid by the previous legislative session has initiated a large-scale overhaul of American infrastructure, with enormous investments across various sectors over the next 5-10 years.
Industry insights, such as a 2023 survey by Construction Dive, indicate that contractors including EMCOR, are beginning to see the tangible benefits of these federal investments. In the recent earnings call, EMCOR’s Chairman and CEO Tony Guzzi shared the company’s engagement in projects that leverage these federal investments in sectors such as solar energy and electrical infrastructure, as well as the recent reshoring trend. Guzzi highlighted,
“The solar is just starting to reengage in our part of the world, and we have great capability there, supported by the IRA and government incentives. We are privileged to be able to leverage union labour or apply our prevailing wage experience and apprenticeship programs in the nonunion world to execute these projects.”
Moreover, EMCOR has experienced significant momentum in data center construction, driven largely by the AI boom.
“We’ve been leaders in data center construction since the early 2000s,” Guzzi noted, “These facilities have evolved from 5 to 100 megawatt capacities, driven by increasing demand for cloud services and AI-powered systems.”
The growth in data center construction is substantial, with the market expected to reach US$55.36 billion by 2028, growing at a compounded annual growth rate (CAGR) of 11%. Similarly, data storage capacity is projected to more than double by 2027, highlighting the critical need for EMCOR’s services in an increasingly digital and AI-driven world.
The surge in needs to support advancements in AI, electric vehicle supply chain, and cryptocurrency mining creates a dual opportunity for EMCOR. On one hand, the booming demand for manufacturing facilities, data centers, and other infrastructure aligns perfectly with EMCOR’s expertise in building services. On the other hand, the corresponding spike in energy requirements presents a significant opportunity for EMCOR to leverage its capabilities in infrastructure services. As energy demands escalate due to the expansion of high-tech industries, EMCOR is well-positioned to address both the building and modernisation of essential infrastructure, effectively turning these challenges into a growth engine for the company.
Recent Results Surpassing Expectations
EMCOR concluded fiscal year 2023 with robust results. The company reported annual revenue of US$12.6 billion, a 13.6% increase from the previous year, with organic growth nearly matching at 12.6%. Notably, earnings per share (EPS) surged by 65% over the same period, highlighting significant profitability improvements.
This upward trend continued into the first quarter of 2024, with EMCOR surpassing expectations. The company achieved quarterly revenues of US$3.43 billion, up 18.7% year-over-year, and a remarkable 79.7% increase in diluted EPS to $4.17. These strong performance metrics led EMCOR to revise its 2024 guidance upwards, now anticipating revenues between US$14 billion and US$14.5 billion and EPS in the range of US$15.50 to US$16.50.
EMCOR’s outlook is supported by a solid balance sheet, characterised by a low debt-to-capitalisation ratio and substantial cash reserves of US$840 million. This financial stability positions the company well for sustained growth and investment in key areas.
Investments in energy efficiency, sustainability, and advanced technologies like BIM software, prefabrication, automation, and robotics are driving operational improvements. These technologies not only enhance project efficiency and reduce timelines but also align EMCOR with evolving regulatory trends and market demands for greener practices and energy-efficient infrastructure. The successful integration of these technologies is evident in EMCOR’s improved operating margins over the past two years, positioning the company for continued competitive advantage and potential profit margin expansion.
The TAMIM Takeaway
Looking ahead, EMCOR is well-positioned to capitalise on the expanding infrastructure and technology sectors. The company stands to benefit significantly from federal investments like the IIJA and IRA, which are expected to drive demand for EMCOR’s services in large-scale infrastructure projects. Additionally, EMCOR’s involvement in technological advancements, particularly in data centers and AI, positions it at the forefront of industry developments.
In essence, EMCOR represents a convergence of opportunity and stability, making it an attractive long-term investment for benefiting from infrastructure development and technological progress.
Disclaimer: EMCOR Group Inc. (NYSE: EME), Meta (NASDAQ: META) and Alphabet (NASDAQ: GOOG) are held in TAMIM Portfolios as at date of article publication. Holdings can change substantially at any given time.
While flashy industries and businesses often capture the imagination of investors, it’s the understated, “boring” businesses that often form the backbone of solid portfolios.
These companies may not make headlines, but their stable, predictable revenue streams and resilient business models, serve as the bedrock of many portfolios. Renowned investors, such as Warren Buffett and Peter Lynch, have often lauded the virtues of these unglamorous yet resilient enterprises.
Buffett, the “Oracle of Omaha,” champions the philosophy of investing in businesses with enduring competitive advantages and predictable cash flows. His conglomerate, Berkshire Hathaway (NYSE: BRK), thrives on acquiring and holding onto such boring yet dependable companies like insurance giants and consumer brands.
Similarly, Lynch, known for his prowess at Fidelity Magellan Fund, advocated for investing in what you know and understand. He favoured businesses with simple, understandable models that consistently deliver results, often found in industries like utilities or consumer staples.
Investors flock to these stalwarts for their reliability and ability to weather economic storms with steadfast resolve.
Across the globe, stalwarts like Procter & Gamble (NYSE: PG) in consumer goods, Johnson & Johnson (NYSE: JNJ) in healthcare, and Berkshire Hathaway in diversified holdings exemplify the power of boring businesses. These companies thrive not on the hype of innovation, but on the bedrock of reliability, making them sought-after gems in any investor’s portfolio.
The Company
A little closer to home, small cap company Servcorp Limited (ASX: SRV) fits this mould.
It is a leading provider of Executive Serviced and Virtual Offices, Coworking, and IT, Communications, and Secretarial Services. The company was founded in 1978 and is still led to this day by Alf Moufarrige. Servcorp began as a solution to the overhead costs of traditional office setups. Since then, it has expanded globally, pioneering concepts like the Virtual Office in 1980 and boasting a presence in 129 locations across 40 cities in 20 countries. With a commitment to supporting businesses’ growth and success, Servcorp offers premium locations, state-of-the-art facilities, cutting-edge technology, and dedicated support teams.
The Headline Thieving Competitor
In a highly competitive market, one rival readers will likely be familiar with for all the wrong reasons is global player WeWork.
Founded in 2010 by Adam Neumann and Miguel McKelvey, WeWork initially thrived by offering shared workspaces tailored to freelancers, startups, and companies seeking flexible office solutions. Its innovative business model, fueled by low-interest rates, saw rapid growth, achieving unicorn status with a valuation exceeding US$1 billion by 2014. However, intensified scrutiny ahead of its planned IPO in 2019 exposed concerns over leadership, spending habits, and governance, prompting Neumann’s resignation and a postponement of the IPO.
SoftBank Group’s subsequent bailout and restructuring efforts failed to reverse the company’s fortunes, exacerbated by the COVID-19 pandemic’s impact on office space demand.
Despite a strategic pivot towards catering to larger corporate clients, WeWork’s market capitalisation plummeted post-IPO, accompanied by substantial net losses. With its sustainability questioned amid a changing real estate landscape and macroeconomic challenges, WeWork faces an uphill battle to regain investor trust and viability in an environment of excess supply, diminished demand, and heightened competition.
Since then, the outed CEO, Neumann, has attempted to buy back the business making a bid of over US $500 million and making a Bunnings style offer to beat any other deal by 10%.
It now appears that attempted repurchase has failed with a bankruptcy court judge approving a deal whereby WeWork’s creditors take control of the reorganised entity and invest fresh capital.
The longevity of Servcorp, experienced management and responsible cost control give us confidence that the business will not suffer the same fate as WeWork.
Saudi Arabia Listing
Servcorp is in the process of restructuring its operations in the Middle-East.
The company recently updated the market with details regarding the establishment of a new holding company for the region. Securing a regional headquarters licence from the Saudi Ministry of Investment marks a milestone, granting Servcorp full support for its international initiatives through its Saudi entity.
This progress aligns with Servcorp’s strategy for a planned listing of its Middle East and European operations in 2025. With Servcorp retaining a 55% stake in the new entity, profit targets for 2024 are on track, supported by the construction of four new locations to meet demand. The potential listing promises value enhancement for shareholders, leveraging strong growth market multiples in Saudi Arabia.
A Strong Financial Position
Servcorp reported their first half results in February with total revenue growing by 8.5% to $157 million.
The company stated that the effective execution of Servcorp’s business model, centred around delivering prestigious experiences and tailored workspace solutions to meet each client’s specific needs, not only propelled revenue growth but also facilitated steady improvements in client satisfaction and retention, resulting in heightened business efficiency and reduced business development costs. This was a key driver in the 31% increase in earnings per share for the first half to 20.2 cents.
Servcorp is supported by a strong cash position with $95 million in cash on hand as of 31 December 2023. Furthermore, it has consistently returned capital to shareholders paying a dividend of $0.12 per share in each of the previous 6 months with a dividend yield of 5.71% at the time of writing.
The company reaffirmed its FY24 guidance despite the highly competitive market. Servcorp expects an additional 7 new operations to commence in FY24 which supports the forecast underlying net profit before tax between $50 million and $55 million with the expectation to produce at least $70 million in free cash flow.
The TAMIM Takeaway
Servcorp epitomises the essence of a “boring” yet robust business model that stands the test of time.
The company’s global footprint highlights its strong geographical diversity and resilience in navigating diverse market landscapes. As the company continues to deliver premium solutions tailored to meet the evolving needs of businesses worldwide, its virtual office tailwinds position it for sustained growth and success. Moreover, Servcorp’s dedication to returning capital to shareholders, underscored by consistent dividend payments and a strong financial position, reinforces investor confidence in its long-term sustainability.
Amidst the market headlines and high multiples of flashy technology like AI, Servcorp’s steadfast performance and prudent management instil confidence in a company that can navigate challenges and deliver value to stakeholders, making it a compelling investment proposition for steady, dependable enterprises.
Disclaimer: Servcorp Limited (ASX: SRV) is held in TAMIM Portfolios as at date of article publication. Holdings can change substantially at any given time.