This week’s reading list is about labels that have quietly stopped describing the thing they name. American companies posted 57 per cent aggregate earnings growth last quarter, which sounds splendid until you notice that more than half of them reported earnings going backwards, and Damodaran does the unglamorous work of separating the accounting from the cash. America did not lose its rare earth industry, as the usual telling has it; it sold the thing, one individually sensible transaction at a time, until the equipment from the last magnet plant was on a boat. A million AI agents turn out to buy speed rather than intelligence, with the gains flattening somewhere around eight. A 60/40 portfolio left alone since 2020 is now a 77/23 portfolio, whatever the statement still calls it. Deloitte is alleged to have signed accounts as true and fair while sometimes relying on documents it had helped produce. A Japanese residence category meaning “nationality not confirmed” leaves its holders stateless, which is not a nationality but is printed where one ought to be. And the most pristine coral reefs in the Pacific turn out to run largely on bird droppings. The useful lesson for investors is that labels tend to be maintained by whoever benefits from them. The best investors are not taking the description on trust. They are checking what is actually in the box.
📚 Stock Prices, Earnings and Cashflows: The AI Effect plays through! Markets added US$2.5 trillion of capitalisation in September, almost US$1.5 trillion of it technology, while the ten year Treasury rose 54 basis points, a move in the top decile since 1962. Aggregate second quarter net income rose 57 per cent, though more than half of companies reported net income falling, and capex was up US$133 billion year on year. His implied equity risk premium has dropped below 4 per cent for the first time this year. (Musings on Markets)
📚 America Didn’t Lose Its Rare Earth Industry. It Sold It. Kirsten Asdal, Tom Koch and Tao Tan on how a market worth under US$10 billion came to control an enormous amount of downstream value. China refines more than 90 per cent of the world’s rare earths and close to 99 per cent of the heavy ones, having bought General Motors’ magnet unit in 1995 and watched the last US plant close by 2006. Each sale was rational on its own terms, which is rather the point. (Lawfare)
📚 Can a Million AI Agents Create Superintelligence? Ramez Naam, guest posting, tests Dario Amodei’s “country of geniuses in a datacenter” against the measurements. Going from ten agents to a hundred added about 27 points on a formal maths test; the next tenfold step added two. On one security benchmark, one agent scored 71.2, four scored 74.3 and sixteen scored 76.4, and a separate study found gains flatten after about eight. (Noahpinion)
📚 Is It Time to Rebalance Your Portfolio? Ben Carlson on the allocation you have rather than the one you chose: a 60/40 portfolio untouched since the start of the decade has drifted to roughly 77/23. High quality bonds now yield above 5 per cent for the first time in almost twenty years, so a balanced portfolio no longer needs heroic equity returns to hit a 7 per cent target. He concedes rebalancing is psychologically hardest precisely when it matters most. (A Wealth of Common Sense)
📚 How Deloitte allegedly helped Abramovich hide $10bn: Simon Lock on claims that Deloitte Cyprus and a spin-off falsified at least 1,000 corporate records across more than 100 companies, backdated by up to five years between 1999 and 2013. The firm is alleged to have acted as nominee director, shareholder, administrator, accountant, tax adviser and independent auditor simultaneously. Deloitte Cyprus says it acts in compliance with applicable laws; Abramovich’s lawyers deny any knowledge of unlawful backdating or concealment. (The Bureau of Investigative Journalism)
📚 Don’t Trust People Who Talk Like This: Ted Gioia watches David Ellison, fresh from a US$111 billion Warner Bros deal underwritten by US$40 billion of his father’s personal guarantees, explain that he is “positioned to win in every single vertical” with “marquee intellectual properties”. Gioia’s subtitle is the test: the beginning of wisdom is calling things by their right names. A portable instrument for reading company announcements. (The Honest Broker)
📚 The Tao of Tao: Terence Tao on where AI actually changes his working method and where it does not. He now runs what he calls clinical trials of mathematical methods across datasets of more than 10,000 problems, previously impractical, under a three year US$5 million DARPA grant. His image for unverified AI output is a firehose of undrinkable water, with formal verification as the filter, and he notes the machine “is not grounded in any actual understanding”. (UCLA Magazine)
📚 Why I Remain Stateless: A Short History of Chōsen-seki: Taejun Shin is 45, runs a financial group across seven countries, has entered about twenty countries for work, and holds no passport because he holds no nationality. His Japanese residence card records a 1947 designation meaning only that his nationality has not been confirmed, a category that has fallen from roughly 600,000 holders to about 22,000. He could have opted out decades ago and describes why he has not. (Taejun’s Substack)
📚 Some of the most pristine coral reefs have a secret weapon: birds: Lauren Sommer from Palmyra Atoll, where seabirds across almost 200 atolls were estimated to deliver more than 100,000 pounds of nitrogen, a nutrient trail running from forest to reef and showing up in plankton, fish and manta rays. Rats arrived in the Second World War and peaked at perhaps 30,000; since 2019 more than a million coconut palms have been removed. Researchers first noticed the connection because manta rays were clustering near bird colonies. (NPR)
📚 The Many Failures of Larry David: Blake Harris on a man who sold irregular bras on Broadway, drove a limo, and would walk offstage mid set if he felt disrespected. He demanded his name be taken off his first sitcom script, and the Seinfeld pilot tested so badly it was renewed for four episodes, possibly the shortest order on record. Shooting at Yankee Stadium years later, the one fan yelling that he sucked stuck with him more than the fifty thousand cheering. (Colossus)
There is a familiar ritual whenever a well known stock falls 30%. Someone at a barbecue declares it “on sale”. Someone else warns about catching a falling knife. Both are usually answering the wrong question. A lower share price tells you the market is paying less for a business than it was last month. It does not tell you why, and understanding why share prices fall is close to the entire investment decision.
Markets reprice in hours. Businesses change over quarters and years. Over long periods the two tend to converge, because a share is ultimately a claim on the cash a business generates. Over shorter periods they can drift a long way apart, and that gap is where both the opportunity and the damage sit.
When a share price falls sharply, there are broadly three explanations. The business may be earning less, which is earnings deterioration. The market may be paying less for the same, or even growing, earnings, which is valuation compression. Or something fundamental may have changed in the business or its industry, impairing what it can earn in future, which is structural risk. Each calls for a very different response, and many of the most expensive mistakes in equity investing come from mistaking one for another.
Why share prices fall matters more than how far
Recent years have provided textbook examples of all three. In 2022, rising interest rates sharply derated growth stocks, many of which kept growing their earnings throughout. Cyclical businesses have cycled through earnings downgrades as demand softened and recovered. And the rapid progress of artificial intelligence has investors asking, sometimes loudly, whether entire industries face a permanent reset in their economics.
In each case the share price chart can look much the same. A stock is down 35% from its high. What sits underneath that chart is very different, and so is the right response. Understanding why a falling share price has fallen is therefore not an academic exercise. It is the difference between a patient contrarian investment and an expensive lesson.
Earnings deterioration: when the numbers start to weaken
Earnings deterioration is the most intuitive of the three. Revenue growth slows, margins contract, costs rise or cash conversion weakens. In more severe cases, profits fall outright.
Not all of it is permanent. Consider a well run industrial business whose customers start delaying capital expenditure. Revenue growth slips from 15% to 5%, and margins narrow as fixed costs are spread across lower volumes. Analysts cut their forecasts and the share price follows.
To put numbers on it, imagine the company earns $100 million a year and the market values it at 20 times earnings, a market capitalisation of $2 billion. In the slowdown, earnings fall to $80 million and the market trims its multiple to 17 times. The company is now worth $1.36 billion, a fall of 32%.
The investor’s job is to judge whether $80 million is a temporary trough or the start of a longer decline. If earnings recover to $110 million and the market returns to 20 times, the business would be worth $2.2 billion, roughly 62% above the depressed value. If the weakness persists, that apparent upside was never really there.
The useful questions here are practical ones. Is the weakness specific to the company or shared across the industry? Are revenues falling because customers are pausing, or because they are leaving? Is margin pressure cyclical, or has the cost structure changed for good? Is cash flow weakening faster than reported profit? Can the balance sheet carry the business through a longer downturn than management expects? And are management’s medium term targets still credible, or merely still published?
A falling earnings forecast is not, on its own, a reason to sell. It is a reason to understand the cause, the likely duration and how recoverable the decline really is.
Valuation compression: when the business performs and the share price does not
Valuation compression is perhaps the most frustrating experience in long term investing. The company does almost everything right, growing revenue, profit and cash flow, and the share price falls anyway.
This happens when investors become less willing to pay a premium for those earnings. Higher interest rates lift the return available from lower risk assets and raise the discount rate applied to future cash flows. Sentiment rotates from growth towards defensives, resources or income. Sometimes an industry simply falls out of fashion, as industries periodically do.
The arithmetic can be startling. Take a company earning $100 million and trading at 30 times earnings, valued at $3 billion. Over the next year it grows earnings by 20% to $120 million. Meanwhile rates rise, enthusiasm fades, and the market now pays 20 times. The company is worth $2.4 billion. Earnings are up 20% and the share price is down 20%. Nothing went wrong with the business; the market simply decided each dollar of profit was worth less.
For a genuinely high quality business, this can improve the return available to a new investor. Buying at 20 times earnings rather than 30 means paying considerably less for the same profit base. If the company keeps compounding, the investor can do well even if the multiple never returns to its old peak. A good investment does not always require the market to become more excited about a company. Sometimes it only requires the business to keep growing into its valuation.
The caveat matters just as much. Compression is not automatically a buying opportunity. A stock at 20 times can still be expensive if its sustainable growth is modest, its competitive position is eroding or rates stay higher for longer. The most common trap is anchoring to the old multiple and assuming the stock is cheap because it once traded higher. The old multiple may have been the mistake.
Structural risk: when the thesis may be broken
The third category is the most dangerous, largely because it rarely announces itself. Structural risk arises when something threatens the long term economics, competitive position or viability of a business, and unlike cyclical weakness or a sentiment driven derating, it does not necessarily reverse when conditions improve.
It can take several forms. A new technology can make a product less relevant or rewrite an industry’s economics. A competitor can arrive with a lower cost base or a better distribution model and permanently reduce incumbent profitability. Regulators can change the rules on capital, pricing or what a business is allowed to do. A company can become dependent on funding that is no longer available on sensible terms. Customers can shift for good to another product or channel. And governance can fail, through weak oversight, poor capital allocation or numbers that turn out to be less reliable than they looked.
The difficulty is that structural decline usually begins by looking like ordinary earnings weakness. Management attributes a soft result to temporary factors. Investors assume margins will mean revert. The economics, meanwhile, may already have changed.
This is how the classic value trap is built. Consider a business that historically earned $100 million and traded at 15 times, worth $1.5 billion. After a heavy sell off it is worth $750 million, apparently just 7.5 times historical earnings. But if disruption has reduced sustainable earnings to $50 million, the company is trading at 15 times its new earning power, exactly where it started. If earnings keep falling, the “cheap” stock becomes progressively more expensive. It looks inexpensive against yesterday’s profits, not against tomorrow’s.
Historical profitability offers very little protection once the underlying economics of a business have changed.
The three rarely arrive one at a time
In practice, these categories overlap. Higher rates can compress valuation multiples while also lifting borrowing costs and cooling demand, hitting earnings at the same time. An industry facing regulatory uncertainty may be derated well before the earnings consequences become visible. Disruption often shows up first as a loss of investor confidence, then as slowing revenue growth, and only later as falling profit.
That makes the analytical job one of apportioning blame. How much of the fall reflects earnings deterioration that is already visible? How much reflects a change in what investors are willing to pay? And how much is the market pricing in a more fundamental threat that has not yet reached the accounts?
This matters most in periods of stress, when markets tend to sell indiscriminately. Some businesses genuinely become less valuable. Others merely become less popular. Occasionally, a high quality company becomes a materially better investment precisely because it has been lumped in with the rest.
Pulling a share price fall apart
A simple discipline helps. At its most basic, a share price is earnings per share multiplied by the price to earnings multiple. Decomposing a fall into those two parts often clarifies what has actually happened.
Scenario
EPS change
P/E change
Share price change
Earnings growth, stable valuation
+20%
0%
+20%
Earnings growth, multiple compression
+20%
-30%
-16%
Earnings decline, stable valuation
-20%
0%
-20%
Earnings decline and multiple compression
-20%
-25%
-40%
Stable earnings, multiple expansion
0%
+25%
+25%
The same business can produce very different investment outcomes depending on what the market is prepared to pay for its earnings. The framework is deliberately simplified. Real valuations also have to account for debt, cash flow, capital requirements, dilution and how durable future earnings are likely to be.
Alongside the arithmetic, a short set of questions does most of the work. Have earnings expectations changed, and by how much? Has the multiple contracted, and from what starting point? Has the competitive position weakened? Has the balance sheet become riskier? Are cash flows supporting reported profit? And, most importantly, has the original investment thesis changed, or only the share price?
Balance sheets decide who gets to wait
One of the clearest dividing lines between companies that recover from a downturn and those that do not is financial resilience. Businesses with strong balance sheets, recurring revenue, solid cash generation and defensible market positions have options when conditions deteriorate. They can keep investing while competitors retrench, retain good people, fund product development and pick up weaker rivals at attractive prices.
Heavily indebted companies tend to have the opposite problem. They may be forced to raise equity at depressed prices, sell assets or cut investment at precisely the wrong moment. A temporary earnings dip can become a permanent loss of shareholder value simply because the balance sheet could not absorb it.
Quality, however, is never the whole answer. A wonderful business bought at an excessive price can still deliver disappointing returns. An ordinary business bought cheaply enough can do well, provided the risks are properly understood. The objective is not to find the best companies in the abstract, but to find investments where the relationship between price, quality, risk and prospective return is genuinely compelling.
Patience is not the same as stubbornness
Each type of decline demands a different kind of thinking. Earnings deterioration is analysed through the likely depth and duration of the cycle. Valuation compression requires a view on sustainable growth, discount rates and a reasonable future multiple. Structural risk requires reopening the investment thesis itself.
Time horizon matters enormously. An investor with a short horizon, or capital that may need to be withdrawn at the wrong moment, can be forced to sell into volatility even when the business is intact. A patient investor with appropriately structured capital is far better placed to take advantage of temporary dislocations.
Patience, though, should not become a polite word for ignoring new information. Holding a strong business through a period of market pessimism is very different from holding on to a thesis the evidence no longer supports. Long term investing requires conviction, and it also requires the intellectual flexibility to change one’s mind when the facts change.
The limits of the framework
It would be convenient if every falling share price came neatly labelled. It does not, and the framework has real limitations worth acknowledging.
The categories are often only obvious in hindsight. A structural decline and a cyclical downturn can look almost identical for several reporting periods, and the market frequently has information, or at least suspicions, that have not yet appeared in the numbers. When the market is sceptical, it is not always wrong.
Management commentary is an imperfect guide. Executives have every incentive to describe weakness as temporary, and they are sometimes the last to accept that their industry has changed.
The arithmetic also has blind spots. Price to earnings multiples ignore debt, so a company can look cheap on earnings while carrying a balance sheet that makes the equity fragile. Reported earnings can flatter cash generation. And a stock that has derated can keep derating if rates or sentiment move further against it; a lower multiple is a starting point, not a floor.
Finally, there is the behavioural risk on the investor’s side. Having owned a stock at a higher price, it is very tempting to classify its fall as valuation compression because that is the explanation that requires the least admission of error. The framework only works if it is applied honestly.
What should long term investors actually do?
The lesson is not to buy every fall or to flee every one. It is to slow down and diagnose before acting.
For long term investors, the practical question after a sharp decline is what has changed: the earnings, the multiple or the business itself. Decomposing the move into earnings and valuation, checking whether cash flow supports profit, and testing whether the balance sheet can survive a longer downturn than expected will usually answer more than any chart.
Where a business remains financially sound, competitively strong and capable of growing sustainable earnings, a lower price may create a more attractive entry point. Where earnings weakness looks cyclical and recoverable, there may also be opportunity, provided the valuation compensates for the uncertainty. Where the economics look structurally impaired, a lower share price alone is not a reason to invest, however tempting the old multiple makes it look.
TAMIM Takeaway
A falling share price is a symptom, not a diagnosis. It can reflect a business earning less, a market paying less for the same earnings, or a business whose future earning power has been permanently reduced. Those three situations can look identical on a chart and lead to very different outcomes.
The market is often quick to punish all three equally, which is precisely why the distinction matters. Earnings deterioration calls for analysis of the cycle. Valuation compression can create genuine opportunity in quality businesses. Structural impairment calls for caution, however cheap the stock appears against its history.
For long term investors, the discipline is to stay anchored to the relationship between the price paid today and the cash a business can realistically generate over time. Volatility is inevitable. Permanent capital loss is far more often the product of misreading why a price has fallen than of the fall itself.
Disclaimer: This article provides general information only and does not constitute personal financial advice. It does not take into account any individual’s objectives, financial situation or needs. Investing involves risk, including the potential loss of capital. Investors should consider the relevant offer documents and seek professional advice where appropriate before making an investment decision.
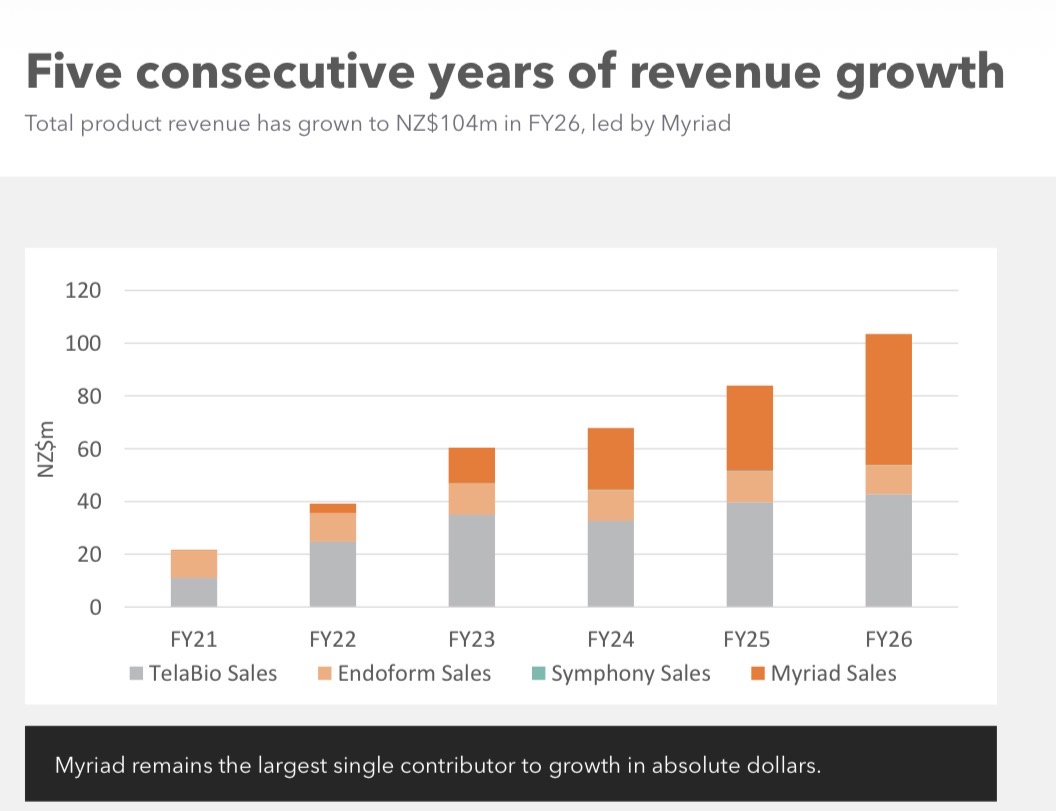
One of the enduring truths in small cap investing is that the market is very good at pricing what a company earned last year and rather poor at pricing what it is quietly building. Aroa Biosurgery is a good example. The business has just delivered five consecutive years of revenue growth, beaten its own guidance on both revenue and profit, finished the year debt free, and published a randomised trial for its next product. The share price has done very little about any of it, and is down for the calendar year.
Part of the reason is that Aroa is not an easy company to put in a box. It is a New Zealand soft tissue regeneration company listed on the ASX (ARX) that sells mostly into US hospitals, takes its raw material from sheep, and reports in New Zealand dollars. It is also about to report a lower EBITDA number in FY27 than it did in FY26, by choice. None of that suits a market that likes simple stories and rising lines, and we think that is exactly where the opportunity sits.
What Aroa actually does
Aroa takes ovine forestomach tissue and processes it into an extracellular matrix, essentially a natural scaffold that the body can use as a template for repair rather than a permanent synthetic mesh. Surgeons and wound clinicians use these bioscaffolds when soft tissue needs to regrow, in complex wounds, trauma, hernia repair and reconstruction.
The commercial portfolio is built around three lines. Myriad is sold directly by Aroa’s own US sales force for complex wounds, trauma and lower limb salvage. OviTex and OviTex PRS are manufactured by Aroa and distributed by Nasdaq listed TELA Bio into hernia and breast reconstruction. Endoform is an older wound product. Symphony, a skin substitute that combines Aroa’s matrix with high molecular weight hyaluronic acid, is the next commercial bet, aimed at hard to heal diabetic foot ulcers and venous leg ulcers in the outpatient setting.
Source: Aroa Biosurgery, investor presentation, 19 August 2026. Product revenue has grown every year since FY21, with Myriad (dark orange) now the largest single line.
The FY26 result was a Myriad story
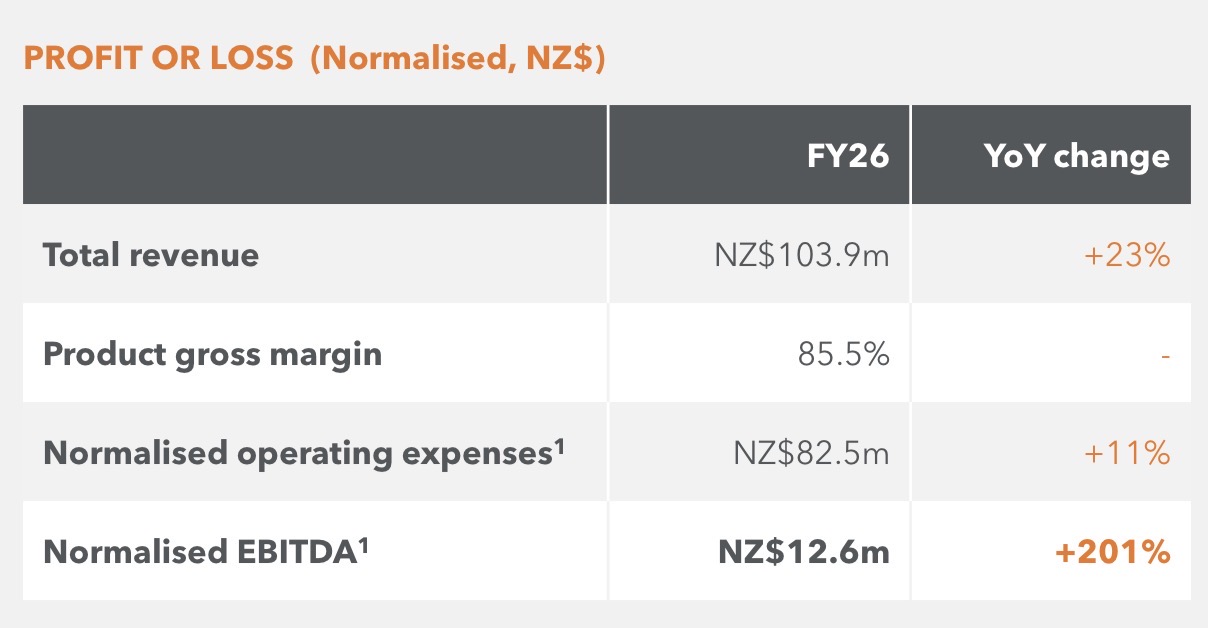
The financial story in the year to 31 March 2026 was Myriad. Group revenue rose 23% to NZ$103.9 million, comfortably above the constant currency guidance range of NZ$92 to 100 million. Myriad product revenue was NZ$49.5 million, up 54%, and for the first time larger than OviTex. Direct sales reached 59% of product revenue. Product gross margin held at 85.5%, almost unchanged on the year before.
The most telling detail is how that growth was achieved. Chief executive Brian Ward noted that Myriad’s 54% growth came with the same number of salespeople as the previous year. In small caps we spend a lot of time looking for evidence of operating leverage, rather than assuming it. This is evidence.
Mix matters here too. Management describes Myriad as a product family with a gross margin above 90%. OviTex, sold without a dedicated Aroa sales force, carries a lower margin, with the company citing about 75%. Every dollar of growth that comes from Myriad rather than OviTex makes the group a little more profitable.
Source: Aroa Biosurgery, FY26 results. Normalised figures are non GAAP measures.
Normalised operating expenses were NZ$82.5 million, up 11% against 23% revenue growth. Normalised EBITDA was NZ$12.6 million, three times the NZ$4.2 million of FY25 and well ahead of guidance of NZ$5 to 8 million. Operating cash flow was NZ$10.5 million.
A clean balance sheet, and a deliberate investment year
Aroa finished FY26 debt free, with NZ$27.1 million of cash and term deposits and NZ$5.1 million of net cash generated during the year. For a medical device company of this size, that is an unusually comfortable position. It does not need the market’s permission to execute its plan, which in small caps is worth more than most investors give it credit for.
FY27 is deliberately an investment year. Guidance is revenue of NZ$115 to 125 million, 13% to 23% growth in constant currency, and normalised EBITDA of only NZ$8 to 11 million. The reason is that Aroa plans to put up to about NZ$9 million into commercial leadership, sales headcount and infrastructure for Myriad and the Symphony launch, of which roughly NZ$4 million relates to Symphony. Direct sales are expected to grow 24% to 40%, while sales to TELA Bio are assumed flat.
This is the part the market seems to have struggled with. A headline EBITDA decline looks like a step backwards on a screen. Read properly, it is a profitable, self funded company choosing to reinvest into a channel that has just shown it can grow 54% without extra heads. Those are very different things.
Significant upside, if execution holds
Brian Ward has said he expects revenue growth of more than 20% a year for the next three to four years, and a path toward roughly NZ$200 million of annual turnover. That is management’s ambition, not guidance, and it should be treated accordingly. It is still worth working through what it would mean.
At NZ$200 million of sales, a reasonable estimate of normalised EBITDA is NZ$40 to 65 million, with a central case near NZ$50 million, or a margin of about 20% to 30%. The arithmetic starts from a blended gross margin still in the mid 80s, which would put gross profit at about NZ$170 to 174 million. Operating costs should not double with sales. FY26 already showed leverage, and after the FY27 step up, commissions and some clinical costs stay variable while the sales force and overhead should scale more slowly.
The low end of that range assumes continued heavy commercial investment. The high end assumes better sales productivity and a richer Myriad mix. Aroa has not published an EBITDA target at NZ$200 million of revenue, so this is a scenario, not a forecast from the company.
If Aroa were delivering that earnings base and still growing at a solid double digit rate, a mid teens to low 20s EBITDA multiple would be the plausible market range, centred around 15 to 18 times. On NZ$40 to 65 million of EBITDA, that implies an enterprise value of roughly NZ$500 million to NZ$1.2 billion, before net cash.
Using about 346 million shares on issue, a New Zealand dollar around 90 Australian cents, and only today’s modest net cash, that equity value works out at roughly A$1.40 to A$3.20 a share. A central 15 to 18 times on NZ$50 million of EBITDA gives about A$2.00 to A$2.40.
The stock recently traded around A$0.57, a market value of roughly A$200 million. So the scenario implies a large re-rating rather than a small one, and it assumes little further dilution. The high end needs Myriad and Symphony still growing well and margins moving toward 25% to 30%. The low end fits if growth has slowed to high single digits or the market continues to treat Aroa as a niche wound care name.
Symphony: a disrupted market, and now the evidence
Symphony is the main external tailwind beyond Myriad’s scale up, and the timing has improved markedly this year.
From 1 January 2026, US Medicare set a single flat outpatient rate for most skin substitutes of US$127.14 per square centimetre. For years, outpatient skin substitute pricing had been something of a free for all, with Medicare spending on these products ballooning. The flat rate is expected to push high priced products and costly distribution models out of the market, and to shift more treatment into hospital outpatient departments, where Aroa already has inpatient accounts. A product that was built to be responsibly priced suddenly has a much fairer contest.
In July 2026, CMS proposed keeping that framework, including the same rate, for calendar 2027. That reduces the risk of another abrupt reset. Payers, meanwhile, are increasingly asking for randomised data before they cover advanced wound products routinely.
That evidence arrived on 5 October 2026. A 143 patient randomised trial published in the International Wound Journal found that adding Symphony to standard care closed 55% of Wagner grade 1 and 2 diabetic foot ulcers within 12 weeks, compared with 35% for standard care alone, and cut mean time to closure by 7.8 days, to 65.4 days. The improvement was statistically significant. The lead investigator was Dr David Armstrong, one of the best known names in diabetic foot research, which matters when sales teams sit down with hospital formulary committees.
Symphony is not yet a meaningful revenue line, and coverage decisions still have to follow the data. The tailwind is the combination of a disrupted, price capped market, a product already cleared and sensibly priced, and a published randomised result in a wound that too often ends in amputation.
What could go wrong
A thesis like this needs its risks stated plainly, and there are several.
TELA Bio is a real counterparty risk. OviTex revenue through TELA Bio was NZ$42.8 million in FY26, around 41% of group revenue. TELA’s own business has weakened. In its June quarter, TELA’s revenue fell 4% to US$19.3 million, OviTex PRS unit volumes fell 23%, its net loss widened and new chief executive Heather Getz withdrew full year 2026 guidance while she reassesses strategy. TELA reported cash of US$30.4 million at the time. Aroa’s FY27 guidance already assumes flat TELA sales, but a further deterioration, a restructuring at TELA, or any disruption to that relationship would hit both revenue and the cash flow funding Aroa’s own growth.
FY27 earnings will go backwards before they go forwards. Guidance of NZ$8 to 11 million of normalised EBITDA is below FY26’s NZ$12.6 million. If the new sales investment takes longer to become productive, the market may lose patience well before the leverage shows up. Bell Potter, which covers the stock, trimmed its EBITDA forecasts after the result while leaving revenue expectations broadly intact, which captures the tension well.
Symphony could be slower than hoped. A published trial does not equal coverage, and coverage does not equal sales. Outpatient wound care is crowded, hospitals are slow to change formularies, and Medicare policy in this area has changed sharply twice in two years. A third change is not impossible.
Currency and concentration. Aroa earns mostly in US dollars and reports in New Zealand dollars, so movements in the NZD/USD rate flow straight through reported revenue and margins. The business is also heavily exposed to the US hospital system and US reimbursement settings.
The valuation upside is a scenario, not a promise. It depends on management’s NZ$200 million ambition being met, on margins expanding, and on the market being willing to pay a growth multiple. Any one of those falling short would leave the outcome much closer to the low end, or below it. Further dilution, whether through employee options or a capital raise, would also reduce per share value.
Insider selling. Director John Diddams sold 200,000 shares on market at around A$0.63 on 26 June 2026. It is a modest sale relative to his remaining holding, but it is worth noting, and investors should form their own view.
What should long term investors actually do?
For long term investors, the practical question is not whether Aroa’s FY27 EBITDA line will be higher than FY26. It will not, and management has said so. The question is whether the company is spending its own cash on a channel that has already proven it can grow, and whether the next product has the evidence and pricing position to become a second engine.
On both counts the early evidence is encouraging. The half year result, due on 24 November 2026, will be the first real read on whether the new Myriad sales investment is translating into accelerating direct sales, and on how quickly Symphony is getting into hospital outpatient departments now that the trial is published.
This is a small, illiquid stock with genuine counterparty and execution risk. It is not suited to every portfolio, and position sizing matters. But the market appears to be pricing Aroa as a niche New Zealand wound care company with a struggling distributor, rather than as a profitable, founder led, cash funded device business with a high margin growth product and a newly validated launch.
TAMIM Takeaway
ARX is a founder led, industry leading, cashed up, growing and profitable business, with catalysts and a cheap valuation.
Brian Ward founded the business and still runs it. Myriad is the growth leader inside a high margin soft tissue niche, with OviTex providing partner revenue at no sales force cost. The balance sheet is debt free with NZ$27.1 million of cash, and the company is already growing and profitable on a normalised EBITDA basis, even while it reinvests.
The catalysts are the Myriad sales ramp, the reset in US outpatient skin substitute reimbursement, and the newly published diabetic foot trial for Symphony. The key risk to watch is TELA Bio. At around A$0.57, against a scenario value of roughly A$1.40 to A$3.20 if sales reach NZ$200 million, the entry is cheap relative to that outcome, provided the growth and the multiple both arrive. We think the risk reward is highly attractive.
General advice warning: This article contains general information only and does not take into account your objectives, financial situation or needs. Past performance is not a reliable indicator of future performance. Scenario valuations are illustrative and are not forecasts. Before making any investment decision, consider whether the information is appropriate for your circumstances and seek professional advice if needed.
Disclaimer: Aroa Biosurgery Limited (ASX: ARX) is held in TAMIM portfolios as at the date of article publication. Holdings can change substantially at any time.
Every power station has two numbers. The first is its nameplate capacity, the output it could deliver under perfect conditions. The second is what it can actually be relied upon to deliver at 6pm on a cold, still winter evening when everyone gets home and turns the heater on. Engineers care about the second number. Politicians, press releases and, for a long time, markets have preferred the first.
That distinction is worth borrowing, because the gap between what was promised and what can be delivered is turning up in more than one place at the same time. It is showing up in electricity grids. It is showing up in sovereign debt, most visibly in French government bonds. And, if Ray Dalio’s latest numbers are anywhere near right, it is showing up in the US Treasury market and in the vast pipeline of debt and equity being issued to fund the AI build out.
For long term investors, the common thread matters more than any single headline. Markets appear to be shifting from rewarding promises to pricing deliverability. That shift tends to be slow, then sudden, and it changes which assets deserve a premium.
The 8% problem
Start with electricity, because the arithmetic is cleanest there.
In July, Beijing released the renewable energy plan that sits under its 15th Five Year Plan. The headline target is more than 2,800 gigawatts of wind and solar by 2030, roughly 38 times the capacity of Australia’s entire National Electricity Market. That is the number that travels. As Chris Uhlmann pointed out in The Australian last week, the more interesting numbers are buried further down.
According to Uhlmann’s reading of the plan, China’s planners expect wind and solar to make up around half of installed capacity by 2030 but to produce only around 30% of the country’s electricity. More striking still is how much of that capacity they believe they can count on when the system is under stress. China’s planners call this confidence output, a measure of average available energy across periods of peak demand. Their answer, on Uhlmann’s account, is about 8%. For every 100GW of wind and solar, including farms with batteries attached, planners assume roughly 8GW will reliably show up when it matters.
China has priced that distinction too. Reforms introduced in January pay coal and gas generators for dependable capacity, value batteries according to how long they can keep delivering, and push wind and solar off guaranteed prices and into the market. China has not stopped building renewables, far from it, but its official messaging has shifted from adding capacity to building a system that can actually integrate it.
Uhlmann then applies China’s benchmark to Australia’s Capacity Investment Scheme, which targets 40GW of new capacity by 2030, around 26GW of wind and solar and 14GW of mostly battery based clean dispatchable capacity. On his assumptions (four hour batteries and a prolonged lull in wind and sun), that 40GW shrinks to something closer to 4GW of dependable power. Professor Alex Coram’s point, which Uhlmann quotes, captures the engineering problem neatly: “You can’t buffer your way out of ruin.”
Reasonable people will dispute the assumptions, and energy policy is contested ground. The investment lesson does not depend on who wins that argument. When the system is stretched, reliability becomes scarce, and scarce things get repriced.
France, sovereign debt and the gap between promise and payment
Now swap gigawatts for euros.
Robert Swift, who manages TAMIM’s global portfolios, has rechristened the European problem in his latest commentary. Fifteen years ago the market fretted about the PIIGS. Today the acronym is FROGS: French Republic OATs Go Soggy. The joke lands because the underlying point is serious. The 2012 crisis was resolved largely by deferral, and the fiscal repair job France avoided then is harder now.
The numbers have moved quickly. In February the spread between French and German 10 year government bonds was around 55 basis points. By 5 October it had blown out to roughly 147 basis points, the widest since the eurozone debt crisis, leaving France paying more than Italy or Greece. French 10 year yields are approaching 5%. Public debt sits at roughly 119% of GDP and the 2026 deficit at around 5.4%, both far beyond EU reference levels. France has cycled through four prime ministers since the snap election of June 2024, and the 2027 budget faces Assembly votes on 20 and 27 October, with Moody’s reviewing the sovereign rating on 23 October.
Help from Berlin looks less likely than it once did. Chancellor Merz’s CDU suffered historic losses in two state elections in September, and German voters appear more interested in problems at home than in underwriting a neighbour’s entitlements. As Robert observes, the French have a long tradition of expressing displeasure at changes to their entitlements forcefully, which makes the obvious fiscal fixes politically expensive.
In nameplate terms, France has promised its citizens a level of spending its tax base cannot reliably fund. The bond market is doing what grid planners do, quietly de-rating the promise.
Dalio’s arithmetic: the same problem, much bigger
If France is the live case study, the United States is the main event. Ray Dalio’s note of 13 October, which updates the framework from his book How Countries Go Broke, is long and dense, so it is worth distilling.
His starting point is simple. Countries get into trouble when the supply of debt to be sold is much larger than the demand for it, or when debt service costs rise so far relative to income that they squeeze out other spending. On his numbers, both conditions are now present.
Marketable US Treasuries outstanding were about US$32 trillion at the end of September, 8% higher than a year earlier, with around US$2.1 trillion of net new issuance expected in 2026. Demand for long dated bonds has softened enough that the Treasury has shifted issuance heavily towards short term bills, roughly 50% of issuance against a historical norm closer to 20%. That makes borrowing cheaper today but means more debt must be refinanced sooner, at whatever rate prevails at the time.
Interest is the second squeeze. The average rate on existing Treasury debt is around 3.5%, while market rates sit between 4% and 5.5% across the curve. Every maturing bond therefore rolls into a higher coupon, even if rates go no higher. Dalio estimates that a 1 percentage point rise in the average rate eventually adds around US$310 billion a year in interest, and that interest already absorbs about 21% of federal revenue. Add maturing principal and total debt service is running at roughly 200% of revenue.
The buyers are changing too. Foreign investors hold about 32% of Treasuries and the Federal Reserve about 14%, but recent marginal demand has come increasingly from domestic buyers. Dalio argues that both China and Japan now have reasons to hold fewer US bonds, not more, and that an unwind of Japanese currency hedged positions could be disruptive.
His conclusion is that we are in the middle of the cycle: rates have already risen a long way, but the usual consequences (weaker equities, wider credit spreads, slower growth) have not yet fully arrived.
The new marginal borrower is building data centres
The part of Dalio’s analysis most relevant to equity investors is not about governments at all.
Treasury is competing for capital with every other issuer, and the fastest growing issuer is the AI complex. Hyperscaler bond issuance reached about US$220 billion in the first half of 2026, more than double the roughly US$108 billion issued in all of 2025. Net US corporate debt issuance is expected to rise from about US$700 billion in 2025 to about US$1.4 trillion in 2027. Non financial corporate equity issuance hit an annualised pace of around US$1.8 trillion in the first half of this year, driven by IPOs, secondary raisings and private fundraising by the frontier AI developers.
Dalio describes AI corporate debt as the canary in the coal mine. The logic is straightforward. Higher capital spending funded by more borrowing reduces free cash flow; investors demand wider spreads to absorb the supply; required returns on AI investment rise. That does not mean AI fails as a technology. It means the financing chain is becoming more demanding at the same moment governments are asking the same pool of savers for more money.
There is a pleasing symmetry with the electricity story. Data centres need dependable power, which is precisely the commodity grids are discovering they have overstated. The AI boom is borrowing heavily to build demand for the very thing that is becoming scarce.
How governments usually get out
Robert’s commentary includes a useful framework, listing the five ways governments typically reduce excessive debt. Dalio reaches a remarkably similar list from the opposite direction.
The first is austerity, which is economically sensible and politically unpopular; French streets provide a regular reminder of how unpopular. The second is default, which developed economies avoid for obvious reasons. The third is inflation, which only works if it is concealed, and which is hard to conceal when inflation is already the thing everyone is watching. The fourth is running a global trading empire and effectively appropriating other countries’ assets, the British solution after the Napoleonic Wars and not a realistic option today.
The fifth is financial repression: steering savers, banks and institutions into government bonds at yields below inflation, often under the banner of prudential regulation. US banks held roughly a third of their assets in government bonds in 1947, under 10% by 2008, and around 20% today. There is room for that share to rise again. Dalio’s list adds a sixth outcome, asset prices simply falling far enough to attract buyers, which is the market’s own solution when policy makers do not choose one.
The most likely path, on both men’s reading, is some combination of mild austerity, regulation that nudges domestic savers into government debt, and a quiet acceptance of inflation running a little above target. That is not a crisis scenario. It is a slow transfer from savers to debtors.
What markets may be missing
Put these strands together and a few second order effects emerge.
The era of share buybacks as the default use of corporate cash may be ending. When capital is plentiful and cheap, buying back stock is easy. When governments and AI builders are competing for the same savings, companies that need external funding pay more for it, and companies that fund themselves gain a real advantage.
Long dated bonds may not provide the defensive ballast investors are used to. If the escape route is financial repression, the holders of long duration government debt are the ones being repressed.
Reliability is becoming a priced asset, in electricity and well beyond it. Dependable generation, firm energy supply, essential infrastructure and businesses with genuine pricing power all share the quality grid planners now pay for: they show up when the system is under stress.
Risks and counterpoints
None of this is a forecast of imminent crisis, and there are good reasons for humility.
Dalio himself notes the one historical exception to his template: a genuine productivity and income boom large enough to grow economies out of their debt. If AI delivers on even part of its promise, today’s arithmetic could look very different in five years. The productivity optimists may yet be right.
Policy can delay reckonings for a remarkably long time. Japan has carried government debt above 200% of GDP for years without a classic crisis, and the European Central Bank has tools to cap spreads if it chooses to use them. Markets that look stretched can stay stretched far longer than a sensible investor expects.
On energy, battery costs keep falling and storage durations keep lengthening, and Australian planners would argue that the Integrated System Plan already accounts for firming needs. Uhlmann’s critique is a strong argument, not a settled conclusion. Timing, as ever, is the hardest variable of all. A diagnosis can be correct for years before it is profitable.
What should long term investors actually do?
This is not a call to make heroic macro bets or to sell everything and buy gold. It is a reminder to apply the grid planner’s test to portfolios: distinguish what looks good on paper from what can be relied upon when conditions turn.
In practice, that suggests favouring businesses that generate their own cash and do not depend on cheap external funding; being cautious about valuations that rest on capital staying abundant; questioning whether long dated government bonds will play the defensive role they once did; and paying attention to companies that own scarce, dependable assets, whether that is firm energy capacity, essential infrastructure or a product customers cannot easily do without.
Robert’s global portfolios remain underweight Europe, but he describes himself as dancing close to the door. If French and European politics produce a credible fiscal plan, European equities could re-rate quickly. That optionality is worth keeping in mind, because the moment the obvious solution is adopted is usually the moment the opportunity disappears.
TAMIM Takeaway
French bond spreads have blown out to crisis era levels, Ray Dalio’s numbers show the US debt burden and the AI financing boom competing for the same pool of capital, and even China’s energy planners are quietly discounting most of their wind and solar capacity when the system is under stress. The common thread is a growing gap between nameplate promises and dependable delivery.
The market may still be pricing many assets as if capital will remain cheap and promises will be met in full. For long term investors, the more useful mindset is the engineer’s: value what will reliably show up when conditions are difficult. Self funding businesses, sensible valuations and genuinely scarce assets tend to hold their value when the arithmetic finally catches up with the rhetoric.
General advice disclaimer: This article contains general information only and does not take into account your personal objectives, financial situation or needs. Before making any investment decision, consider whether it is appropriate for your circumstances and seek professional advice if required. Past performance is not a reliable indicator of future performance.
This week’s reading list is about lag, which is to say the inconvenient gap between an event and its consequences. Anthropic has done the arithmetic and found that robots are currently cheaper than people for 0.3 per cent of job tasks, and that on present trends ten per cent arrives in about forty years, which is not the timeline the share prices imply. Indian IT, meanwhile, has already surrendered roughly a third of its market value this year to a disruption that has barely begun. Venice invented the bond market in 1171 entirely by accident, while losing a war, a fleet and a doge, and then never repaid the principal. Postwar British sugar rationing is still turning up in blood pressure readings seventy years later. The time zone database that tells your phone what time it is has one real maintainer, a university lecturer doing it in his spare time. Higher interest rates have been excellent for savers, provided the saver does not also need a mortgage or a car. And a Supreme Court litigator ran two careers in parallel for two decades before the numbers caught up with him. The useful lesson for investors is that the purchase and the bill rarely arrive in the same quarter. The best investors are not trying to time the headline. They are working out which clock started, and when it stops.
📚 What work can robots do? Robots and language models between them touch about 80 per cent of job tasks by working time, which sounds alarming until you reach the cost column. Robots are currently cheaper than humans for 0.3 per cent of tasks, around 300,000 workers, and on a 3 per cent annual price decline it takes roughly forty years to reach ten per cent. Capability, not cost, blocks about 70 per cent of physical work, with manipulation alone accounting for half. (Anthropic)
📚 What Makes Warren Buffett One of a Kind: Jason Zweig, a week after Buffett stood down as chairman at 96 after 61 years, argues the real edge was structural rather than analytical. Berkshire charged no management fee and no performance fee, ran no investment committee, and gave investors no way to add or withdraw capital. The anchor is Alfred Chandler’s line from 1962: unless structure follows strategy, inefficiency results. (Jason Zweig)
📚 The Winners and Losers of Higher Interest Rates: Ben Carlson on who is actually enjoying this. Bills above 4 per cent and quality bonds above 5 are a gift to anyone holding savings and no debt, while mortgages near 7.5 per cent against houses priced for 3 per cent are the opposite. Existing US home sales are running under 4 million a year against more than 5 million around 2000, with 65 million more residents. (A Wealth of Common Sense)
📚 What Will Happen to Indian IT? David Oks on a sector worth about 7 per cent of Indian GDP and a quarter of its exports, employing some 5 million people. Infosys hired 85,000 graduates in 2022 and 12,000 in 2024; TCS announced 12,000 redundancies in July 2025 and Wipro cut 25,000 over two years. TCS, Cognizant and Infosys have each lost about 30 per cent of market value in 2026. (Asterisk)
📚 The 12th-century military disaster that forever changed global finance: Robin Wigglesworth on Venice in 1171, which funded a catastrophic war against Constantinople with forced loans paying 5 per cent and, crucially, made them tradable. The fleet came home ruined by plague, a mob killed the doge, and the republic never repaid the principal. It kept paying the interest out of market taxes instead, and the trade in those loans became the first bond market. (Big Think)
📚 The people holding up the internet: Of 23 critical open source projects examined, eleven are kept running by one or two people. Paul Eggert, a UCLA lecturer, made 218 of the 251 changes to the time zone database in the past year. The maintainer of core-js, which runs on roughly half the world’s top 1,000 websites, asked for US$57 a month in donations and has two sponsors. (Sheets.works)
📚 Swarm Intelligence: Kevin Kelly’s fifty-year forecast is that we stop talking about AI altogether, because it becomes infrastructure: many narrow minds, loosely coupled, noticed mainly when they fail. He thinks the failure mode is systemic rather than dramatic, seizing up if coupled too tightly and flying apart if too loosely. Governing it will look less like engineering than gardening. (Kevin Kelly)
📚 The Tell: Tom Goldstein’s Double Life: Bradley Hope on the man who argued his first Supreme Court case at 28, co-founded SCOTUSblog, and in one eighteen-hour session at the Bellagio in 2008 won about US$400,000 while betting blind on an estimated nineteen hands in twenty. He went to trial in February on sixteen counts, including concealing US$15 million of poker debts from mortgage lenders. All eleven chapters are free. (The Foundry)
📚 The generation raised on sugar rations: Wartime Britain capped adults at about 40 grams of sugar a day and children at under a tablespoon, until sweets came off ration in 1953 and consumption promptly doubled. Those rationed through their first thousand days show a 35 per cent lower risk of type 2 diabetes and a 20 per cent lower risk of high blood pressure, and test about a year younger on biological age measures. An accidental national experiment, still legible seventy years on. (The Guardian)
📚 John Locke: The Playful Philosopher: Henry Oliver’s three-year-old son put a finger into a candle flame to find out what flame was like, which happens to be Locke’s own example in the Essay Concerning Human Understanding. The argument is that knowledge begins in curiosity and direct experiment rather than in system building, and that a practice without play quietly dies. No portfolio application whatsoever. We include it anyway. (Online Library of Liberty)