This week Robert Swift, the Head of Global Equity Strategies of the TAMIM Global Equity High Conviction Individually Managed Account (IMA), reviews JP Morgan in an environment where they are aided by the normalisation of the US interest rate yield curve. In this video, Robert contrasts the fortunes of JP Morgan to that of the Commonwealth Bank.
This week Robert Swift, the Head of Global Equity Strategies of the TAMIM Global Equity High Conviction Individually Managed Account (IMA), reviews JP Morgan in an environment where they are aided by the normalisation of the US interest rate yield curve. In this video, Robert contrasts the fortunes of JP Morgan to that of the Commonwealth Bank.
Stock Picking – JP Morgan Robert Swift – Head of Global Equity Strategies
The Australian smaller companies universe is home to a number of companies which are building global leadership positions in their respective niche markets, and yet somewhat surprisingly remain largely unrecognised in the local investment community. Identifying these types of businesses is both the passion of and the bread and butter of the manager of the TAMIM Australian Equity Small Cap IMA.
The Australian smaller companies universe is home to a number of companies which are building global leadership positions in their respective niche markets, and yet somewhat surprisingly remain largely unrecognised in the local investment community. Identifying these types of businesses is both the passion and the bread and butter of the manager of the TAMIM Australian Equity Small Cap IMA. We will be revealing 6 companies which are achieving great success on a global scale and yet trade on very low valuations in the coming months. Watch this space and read on as the first emerging global leader is revealed in this weeks Stock Picking report.
Stock Picking – Gale Pacific Ltd (ASX:GAP)
The first emerging global leader to be discussed is Gale Pacific Limited (ASX:GAP), a leading global marketer and manufacturer of screening and shading products for domestic, commercial and industrial applications. Way back in the 1970s, GAP invented knitted shade-cloth, and today from their low cost manufacturing facilities in China, the company is one of the world’s largest producers of technical fabrics. The company’s products are extremely durable, do not react to dirt and moisture, and do not rot (like canvas). It seems fitting to us that an Australian company should aim for global leadership in the sun shading and screening market given our position as one of the sunniest countries in the world.
WHY IS GALE PACIFIC TRADING UNDER THE RADAR?
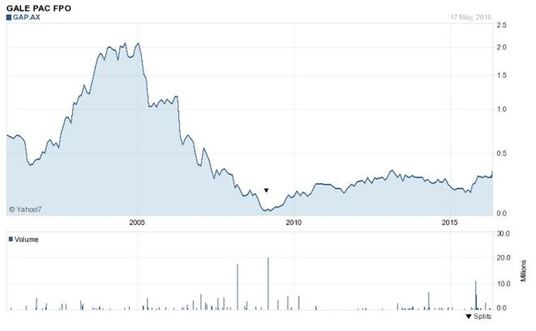
After a period of aggressive, and ultimately unsuccessful, acquisitions during the early 2000’s, GAP has in recent years refocused strategically on its core products and has made significant improvements in its working capital management. The company has been through a period of dramatic restructuring and in our opinion has emerged much stronger and well positioned to grow. The company’s listed journey has involved a dramatic period of under-performance between 2005 and 2009, followed by gradual recovery since then.
This is an interesting backdrop in our opinion. We often find that smaller companies with patchy track records drop off most investors’ radars, even when they are undergoing meaningful restructuring. Investors’ literally forget about them. The market then fails to follow the restructuring and rerate these businesses as restructured businesses which warrant higher valuations. This is smaller company market inefficiency in action. As a result GAP, which is an emerging global leader with excellent growth prospects, is valued at a market cap of under $100m (which implies a very low valuation on all metrics), with a very limited market following. If the broader market were more aware of GAP’s restructuring and post restructuring success, the stock would be trading at a far higher valuation in our opinion. Therein lies the compelling opportunity high quality, under-researched smaller companies present.
LOOKING FORWARD: STRONG FY16 EXPECTED AND ONGOING GROWTH
GAP should deliver revenue growth in excess of 20% for FY16. For the 6 months to 31 December 2015 total sales increased 22%, with sales in Australasia up 18% on the back of new product range wins and improved marketing campaigns. Sales in the Americas region grew 14% in local currency reflecting a broader product range offering and growing market share in both the retail and commercial sectors. Margins have improved through a focus on supply chain improvements (reducing the number of suppliers and improving supplier terms) and inventory management. Management believe there is good potential for ongoing growth in its core global markets in the Americas, Middle East / North Africa and Eurasia, particularly for GAP’s commercial fabrics as the dangers of sun exposure in regions with harsh environments become more widely appreciated. Climate change is likely to provide a tailwind for GAP’s end markets over the very long term as managing sun exposure will become a greater challenge at a global level. GAP’s commercial fabrics are also marketed for a variety of other professional uses, including architecture, horticulture, building and construction, agriculture, transport, water conservation and mining. The company has a multitude of long term growth drivers across its geographies and products.
BUNNINGS AS A MAJOR CUSTOMER: RISK AND OPPORTUNITY
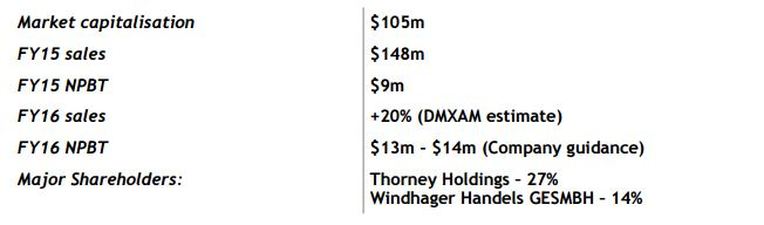
In FY15, Bunnings contributed 35% of GAP’s total $148m in sales (60% of total Australian sales), thus there is an unusually high degree of customer concentration risk. However, from all accounts this relationship appears strong, with GAP taking pride in their ability to work collaboratively with all their customers, including Bunnings. These collaborative relationships provide GAP with consumer insights, new product development initiatives and improved forecasting/inventory management. In addition, Bunnings’ recent expansion into the UK through the acquisition of homewares retailer Homebase, may present an opportunity for GAP to sell product to Homebase which is not currently a GAP customer. We will be watching UK developments closely as this could present a significant opportunity.
COMPELLING VALUATION
At the time of our recent purchase GAP was trading at a discount to its book value. Based on its FY16 guidance of NPBT of over $13m, it is currently trading at around 10x expected ’15/’16 eps of 3.5c, and at 5x ’15/’16 EV/EBITDA). With a 75% payout ratio, this implies a dividend yield in excess of 7%. We view this as significantly under-valued for a business with excellent management and solid growth prospects.
OUR VIEW
GAP is a great example of a smaller company achieving global success in its chosen niche market. We believe management are doing an excellent job of managing the business and we applaud their ambitious international expansion plans. Interestingly, there are currently no brokers covering the stock, but we expect this to change as GAP grows its market capitalisation and earnings, and the company’s market following subsequently increases. If GAP can maintain its current momentum, we expect a share price re-rating driven by both multiple expansion and continued earnings growth. The upside potential is significant, and we are happy long term shareholders.
As is customary, every quarter our partners on the TAMIM Global Equity Growth Individually Managed Account – Calamos Investments – publish their economic outlook.
Introduction
Entering the second half of the year, market participants find themselves facing many familiar unknowns: whether the U.S. and global economies can maintain their muted pace of growth, the potential ramifications of a strong dollar, and the extent to which monetary policy can influence the markets. The political landscape remains a source of apprehension, as investors seek to understand the implications of Brexit and more broadly, global populist sentiment. Yet investor appetite for risk assets has been on the upswing. In this environment, we believe:
Despite signs of deceleration, near-term global economic expansion should continue. The pace is likely to be slow overall and uneven among countries.
Even as U.S. equities have rallied to new highs, downside risk management remains important given the political crosscurrents and macro environment.
Across asset classes, securities with higher quality attributes remain most attractive overall. Growth is likely to outperform, with select opportunities in cyclicals.
The global and U.S. economies are not facing imminent recession, but fiscal policy decisions will be crucial in defining the way forward. It will be hard to break out of a tepid-growth environment without policies and regulations that encourage entrepreneurship and responsible risk taking.
After years of aggressive monetary policy, central banks have limited room to maneuver effectively.
US Equities
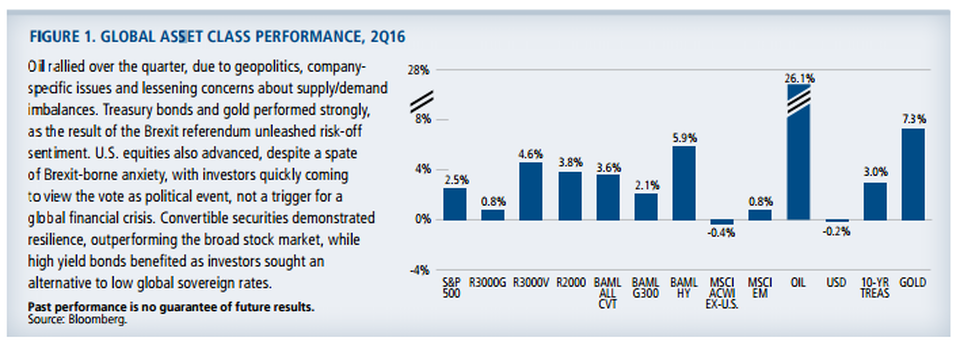
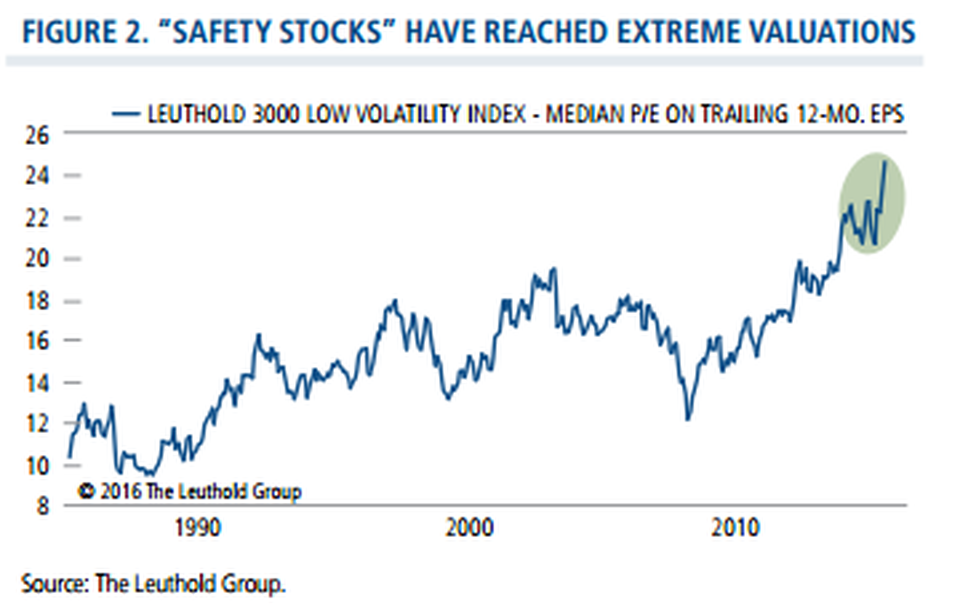
Employment and manufacturing data, as well as signs of wage growth, support our view that the U.S. economy can continue expanding at a pace consistent with recent years, albeit at a lower rate historically seen at this point of the business cycle. The direct impact of Brexit is likely to be contained and provided the dollar doesn’t spike, the U.S. economy should be able to maintain its course. We share in the view that the Federal Reserve is likely to forestall any interest rate increases for the foreseeable future, given the potential economic impact of Brexit and other related political uncertainties. The stock market is likely to remain highly sensitive to economic releases and announcements, as participants seek to make sense both of the data itself as well as how it is likely to influence Fed policy. As the next earnings announcement season commences, guidance is likely to be cautious, especially for currency-sensitive companies. We are devoting particular focus to trends in capex spending, where the impact of euro zone uncertainties is yet to be determined. Investors’ preference for cyclical stocks has faded in the wake of Brexit, with dividend-oriented stocks leading the rebound as investors seek income. However, we are concerned that many of these “safety stocks” are trading at stretched valuations (Figure 2), without offering the long-term growth characteristics we seek. Looking forward, we believe the combination of choppy global growth and lackluster yields worldwide will lead investors to increasingly differentiate between growth versus value. Conditions should support a sustained period of outperformance for U.S. growth stocks with quality attributes, albeit with opportunities for select cyclicals.
Global and International Equities
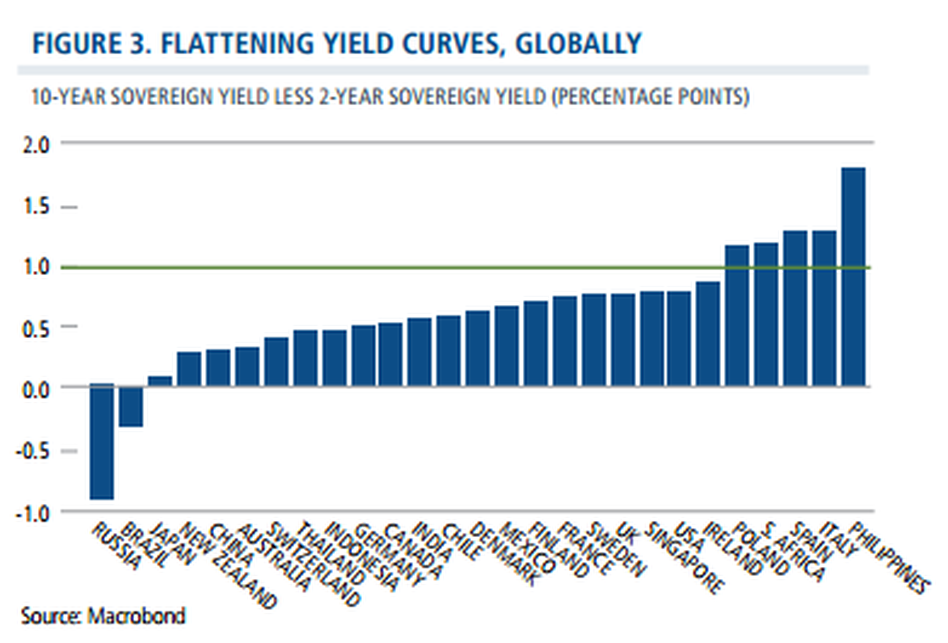
As we noted, we are not calling for a global recession, but do believe that risk management will be especially important in this environment. Although central banks remain committed to monetary policy as required, the efficacy of their actions has become increasingly uncertain. Global yield curves have become much more flat, if not inverted (Figure 3) and absolute yields continue to come down with negative yields for Japan and German 10-year sovereigns.
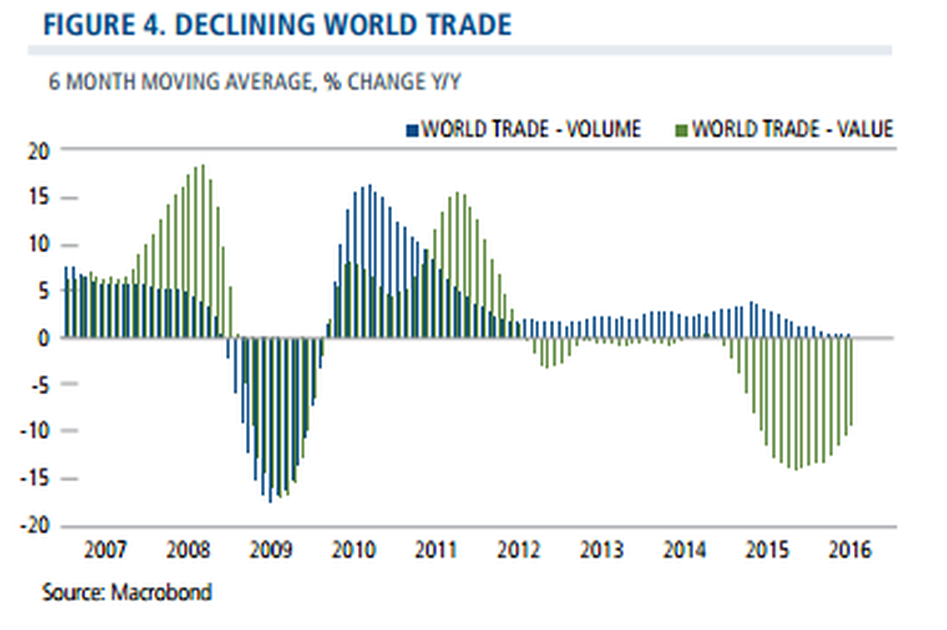
Meanwhile, muted world trade points to lower global growth (Figure 4). While Brexit is not shaping up to be the catalyst for a global financial crisis, we remain vigilant to a potential snowball effect of populist sentiment. These include already-scheduled elections and referendums, as well as calls for exit referendums in a number of other euro zone members.
However, the results of Spain’s postBrexit election suggest that populist momentum may be less than markets originally anticipated following the Brexit result, while the growing near-term economic concerns facing the UK may serve as a further deterrent. Additionally, we may see increased openness to compromises among euro zone members that give periphery countries more latitude. While we are concerned that conversations about the Italian banks haven’t gone particularly well, we are optimistic that an acceptable solution can still be reached. Our strategy in Europe has lately focused on companies with higher quality attributes, such as strong balance sheets and good returns on invested capital. While we have pared exposure to the UK and euro zone more broadly, we continue to identify opportunities in both, including technology, consumer and health care companies with well-recognized global brands and geographically diversified revenue streams. We’re more cautious on UK and euro zone companies that are more dependent on cyclical tailwinds to drive earnings growth, and those that would be more vulnerable to declining business and consumer confidence. We are maintaining exposure to European financials, but are generally underweight in banks, instead preferring beneficiaries of a low interest rate environment, such as real estate names.
In regard to Japan, economic surprises have been on the downtrend over recent months, and a strong yen is a headwind for an export-oriented economy. However, the potential for further monetary policy could help support export industries and beneficiaries of reflation, and we are more likely to see the fiscal policy we believe is essential for sustainable growth. Since the mid-February low, we have become marginally more bullish on emerging markets. Economies with lower-quality fundamentals have continued to perform well, but we remain concerned about the downside associated countries such as Russia and Brazil. We are maintaining our emphasis on countries that are less tied to commodity prices and those which are moving toward higher levels of economic freedoms. Prospects look relatively good in Indonesia and India, both of which have cut interest rates. We are also watching the Philippines with great interest, as new leadership looks set to continue with economic reforms. In regard to China, we continue to believe the government has the tools and levers it needs to prevent a hard landing in the near term. Our focus in China remains on technology and consumption, areas that we believe can benefit from the country’s transition to a more balanced consumer-driven economy.
Alternative Strategies
Volatility during the first half of the year affirmed the potential benefits of strategies that utilize complex volatility trades. For example, options-based strategies provided us with opportunities to capitalize on the conditions that the markets gave us. Given our view of continued volatility, we believe the return profiles of select alternative approaches (such as market neutral and covered call) may be compelling substitutes for traditional fixed income investments, where risk/return profiles give pause. Even though yields are low globally, interest rate risk exists in all environments, which we believe supports the case for strategies structured to avoid duration risk. Elsewhere in the alternative spectrum, long/short approaches may further overall diversification, without the associated risks of the most duration sensitive bonds.
Conclusion
We’ve seen U.S. markets reach new highs over recent days and believe there are continued opportunities for risk assets, globally. Even so, investors should remain selective and prepared for volatility. As we have observed in the past, periods of ebullience can give way to brisker sell-offs when sentiment falters. Whether markets are rising or falling, we encourage investors to let discipline, not emotion, guide decisions. By collaborating and drawing on our range of specialties, we believe our teams are well positioned to identify opportunities and manage the risks in the global economy.
This week Robert Swift, the Head of Global Equity Strategies of the TAMIM Global Equity High Conviction Individually Managed Account (IMA), discusses three key investment thematics that investors need to be aware of heading into this years US election.
This week we feature the third in a 3 series set of articles highlighting the advantages of incorporating Small Company shares in your portfolio. The fund underlying the TAMIM Australian Equity Small Cap Individually Managed Account (IMA) has returned over 32.7% in the 12 months to 30 June 2016. If you would like to discuss this IMA with one of our directors please contact us at ima@tamim.com.au. This opportunity is strictly limited to $100m to protect the portfolio’s investment style and philosophy.
Our 14 Steps to Value Investing
Value investing requires discipline and an ability to see through the noise so as to buy when others are fearful. With a good degree of self-awareness and an open mind we strongly believe it remains a superior investment strategy, and one which can lead to substantial outperformance. This article addresses key value investing terminology and strategies as an introduction to this lucrative investment approach.
Introduction:
The Intelligent Investor by Benjamin Graham remains the value investors’ key reference work 67 years after it was first published in 1949. Warren Buffett has long been a devotee of the principles in this book. The majority of value investing terminology we use today came from this book, such as:
“Investment operation” – “An investment operation is one which, upon thorough analysis, promises safety of principle and an adequate return”.
“Mr Market”: Investors should think of the market as a person, Mr Market, who is usually reasonable and offers you a price for your securities close to your view of fair value, but sometimes Mr Market becomes emotional and volatile, and becomes overly optimistic or pessimistic.
“Margin of safety” – A key tenet of value investing is the idea of factoring in a margin of safety to take into account the fact you may be wrong in your assessment of fair value. e.g. If you think a stock is worth $10, with a margin of safety you may be prepared to pay up to $7 for it. As Mr Graham explains, ”The margin of safety is the difference between the percentage rate of the earnings on the stock at the price you pay for it and the rate of interest on bonds, and that is to absorb unsatisfactory developments”.
OUR APPROACH TO VALUE INVESTING:
At TAMIM Asset Management we are passionate about value investing and believe a disciplined value investing strategy will significantly outperform the market over the long term. We search for companies where the conservatively estimated intrinsic value exceeds the share price by a sufficiently large margin that it affords a margin of safety which maximises the chance of long term outperformance. Our value investing approach is based upon fourteen investment beliefs:
1. Knowledge and expertise are more important than diversification. We believe it is more important to know a small number of companies intimately than to know very little about a lot of companies. Risk increase the more diversified you become. As a result, the TAMIM Australian Equity Small Cap IMA holds only 15 high conviction positions we know extremely well.2. The key valuation measure is cash flow, after allowance for the required capital expenditure to keep the business going over the long term. The intrinsic value will vary over time as cash-flow certainty and the discount rate change.
3. We reject the idea that risk is the standard deviation of historic returns, and believe that risk is the probabilistic assessment of something bad happening (i.e. the distribution has a single tail and is forward looking).
4. The share market can wildly mis-price companies relative to their intrinsic value but over time we believe shares prices will move towards fair value. In the short term, the share market is effectively a popularity contest, but over the long term share prices will reflect economic fundamentals. As a result we are only focused on the long term.
5. We think of ourselves are part owners of businesses. This helps us understand each business better and allows us to take the long term view required.
6. “Mr Market” should be your friend. Bi-polar “Mr Market” provides prices every day – sometimes high and sometimes low. We believe investors should exploit his moods – buy when he is down and sell when he is high. The TAMIM Australian Equity Small Cap IMA has a long term investment horizon which allows us to opportunistically profit from these mood swings.
”Have the courage of your knowledge and experience. If you have formed a conclusion from the facts and if you know your judgement is sound, act on it- even though others may hesitate or differ. You are neither right nor wrong because the crowd disagrees with you. You are right because your data and reasoning are right. Similarly, in the world of securities, courage becomes the supreme virtue after adequate knowledge and a tested judgment are at hand.” – Benjamin Graham
7. We will only invest when we have a sufficient margin of safety. This means there should be a large gap between the intrinsic value and the current share price to allow for any inaccuracies in the assessment of the intrinsic value.
8. We believe management should be invested in their businesses to ensure their interests are aligned with shareholders, and that they treat other shareholders as partners.
9. Investment opinions should be based upon a considered appraisal of a business/investment case against all known facts with the expectation that on average a superior return can be achieved. This contrasts with speculation which is short term and more akin to gambling.
“By speculating instead of investing you lower your own odds of building wealth and raise someone else’s” – Jason Zweig
10. Value investing can be applied to both low and high growth businesses; the key is to invest when the intrinsic value is well above the current share price.
11. The distinction between price, book value and intrinsic value: price is the current share price; the book value is the value of the assets minus liabilities as reported in the accounts; and the intrinsic value is the true underlying worth of the business.
12. Macroeconomic factors are very hard to forecast accurately and, given the long term nature of value investing, frequently of only limited relevance.
“The buyer of bargain issues places particular emphasis on the ability of the investment to withstand adverse developments.” – Benjamin Graham
13. Non income producing assets have no value in the value investing framework.
14. Often family companies perform well because decisions are generally made with a longer time horizon and higher level of engagement in mind.
VALUE INVESTING EXAMPLES:
Buying stocks with a strong asset backing. e.g. We bought into EZA Corp (ASX:EZA) when it was trading at a 25% discount to its net cash value. This may seem surprising but is illustrative of the inefficiencies of the smaller company universe. The stock has since been suspended from the ASX whilst management decide on an acquisition. When the stock re-lists, if a sensible acquisition is announced, we believe the stock will move to a premium to its net cash value which implies significant share appreciation from the acquisition price.
Keeping the portfolio less than fully invested (20% cash on average) in order to keep our powder dry for a market calamity, or to cover any outflows. This has served us well thus far as it allows us to profit whilst others are fearful. We expect to out-perform in falling markets as a result.
Focusing on stocks with a long history of trading so we can effectively analyse and value the businesses. We do not invest in start-ups, we only invest in well established businesses. For example, one of the fund’s top 5 positions is Fiducian (ASX: FID), a leading fund management and financial planning group. The company listed in 2000 (and was established in 1996) which provides a significant amount of data to analyse and thus value the business. As a result we have high conviction that this is an excellent long term investment.
Focusing on low PE stocks – The majority of the fund’s holding are trading on a single digit PE based upon FY16 earnings which represents a significant discount to the market average. e.g. Dental supplier, SDI (ASX: SDI), is currently trading at 8x ’16 earnings, which appears deeply under-valued for a quality international business with solid growth prospects. Investing in such low p/e stocks is a typical deep value investment strategy.
Take a long term investment horizon at the time of investment – Over the past year the fund has only sold 2 of its positions. We do what we say we do in terms of taking a long term view at the time of investment.
We do not set out to replicate the market in any way; we are aiming for significant positive absolute returns – We are completely benchmark unaware as we are looking for the most compelling smaller company opportunities across all sectors. This is how the fund out-performed the All Ords by 53% in the year to March 2016. We remain confident regarding future returns.
Conclusion:
We view true value investing as one of the most potent sources of investment out-performance available. While it is a remarkably simple investment style, it requires immense discipline, patience and dedication. We believe our investors are well placed to benefit.