By Ron Shamgar
One of the enduring truths in small cap investing is that the market is very good at pricing what a company earned last year and rather poor at pricing what it is quietly building. Aroa Biosurgery is a good example. The business has just delivered five consecutive years of revenue growth, beaten its own guidance on both revenue and profit, finished the year debt free, and published a randomised trial for its next product. The share price has done very little about any of it, and is down for the calendar year.
Part of the reason is that Aroa is not an easy company to put in a box. It is a New Zealand soft tissue regeneration company listed on the ASX (ARX) that sells mostly into US hospitals, takes its raw material from sheep, and reports in New Zealand dollars. It is also about to report a lower EBITDA number in FY27 than it did in FY26, by choice. None of that suits a market that likes simple stories and rising lines, and we think that is exactly where the opportunity sits.
What Aroa actually does
Aroa takes ovine forestomach tissue and processes it into an extracellular matrix, essentially a natural scaffold that the body can use as a template for repair rather than a permanent synthetic mesh. Surgeons and wound clinicians use these bioscaffolds when soft tissue needs to regrow, in complex wounds, trauma, hernia repair and reconstruction.
The commercial portfolio is built around three lines. Myriad is sold directly by Aroa’s own US sales force for complex wounds, trauma and lower limb salvage. OviTex and OviTex PRS are manufactured by Aroa and distributed by Nasdaq listed TELA Bio into hernia and breast reconstruction. Endoform is an older wound product. Symphony, a skin substitute that combines Aroa’s matrix with high molecular weight hyaluronic acid, is the next commercial bet, aimed at hard to heal diabetic foot ulcers and venous leg ulcers in the outpatient setting.
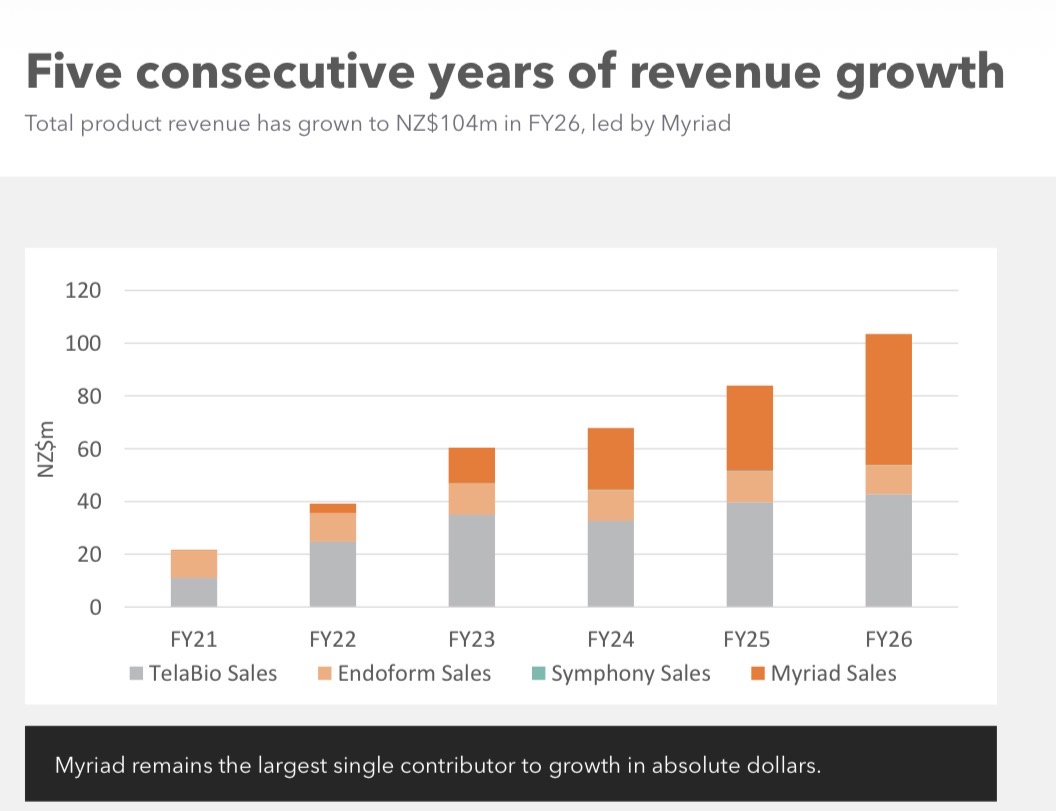
Source: Aroa Biosurgery, investor presentation, 19 August 2026. Product revenue has grown every year since FY21, with Myriad (dark orange) now the largest single line.
The FY26 result was a Myriad story
The financial story in the year to 31 March 2026 was Myriad. Group revenue rose 23% to NZ$103.9 million, comfortably above the constant currency guidance range of NZ$92 to 100 million. Myriad product revenue was NZ$49.5 million, up 54%, and for the first time larger than OviTex. Direct sales reached 59% of product revenue. Product gross margin held at 85.5%, almost unchanged on the year before.
The most telling detail is how that growth was achieved. Chief executive Brian Ward noted that Myriad’s 54% growth came with the same number of salespeople as the previous year. In small caps we spend a lot of time looking for evidence of operating leverage, rather than assuming it. This is evidence.
Mix matters here too. Management describes Myriad as a product family with a gross margin above 90%. OviTex, sold without a dedicated Aroa sales force, carries a lower margin, with the company citing about 75%. Every dollar of growth that comes from Myriad rather than OviTex makes the group a little more profitable.
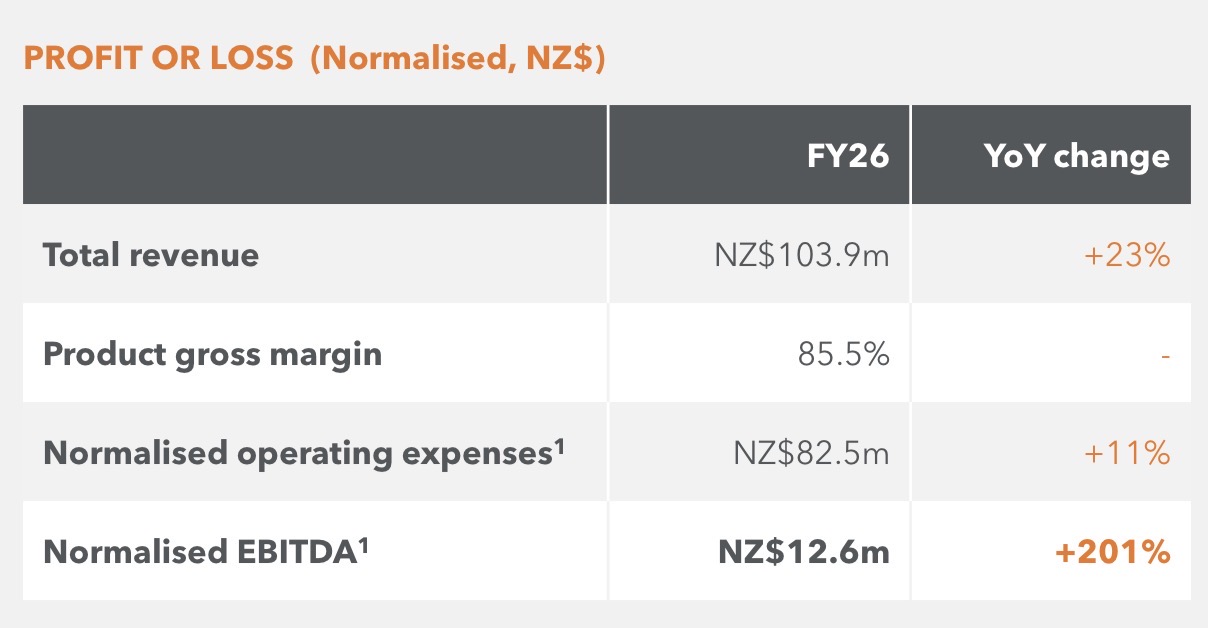
Source: Aroa Biosurgery, FY26 results. Normalised figures are non GAAP measures.
Normalised operating expenses were NZ$82.5 million, up 11% against 23% revenue growth. Normalised EBITDA was NZ$12.6 million, three times the NZ$4.2 million of FY25 and well ahead of guidance of NZ$5 to 8 million. Operating cash flow was NZ$10.5 million.
A clean balance sheet, and a deliberate investment year
Aroa finished FY26 debt free, with NZ$27.1 million of cash and term deposits and NZ$5.1 million of net cash generated during the year. For a medical device company of this size, that is an unusually comfortable position. It does not need the market’s permission to execute its plan, which in small caps is worth more than most investors give it credit for.
FY27 is deliberately an investment year. Guidance is revenue of NZ$115 to 125 million, 13% to 23% growth in constant currency, and normalised EBITDA of only NZ$8 to 11 million. The reason is that Aroa plans to put up to about NZ$9 million into commercial leadership, sales headcount and infrastructure for Myriad and the Symphony launch, of which roughly NZ$4 million relates to Symphony. Direct sales are expected to grow 24% to 40%, while sales to TELA Bio are assumed flat.
This is the part the market seems to have struggled with. A headline EBITDA decline looks like a step backwards on a screen. Read properly, it is a profitable, self funded company choosing to reinvest into a channel that has just shown it can grow 54% without extra heads. Those are very different things.
Significant upside, if execution holds
Brian Ward has said he expects revenue growth of more than 20% a year for the next three to four years, and a path toward roughly NZ$200 million of annual turnover. That is management’s ambition, not guidance, and it should be treated accordingly. It is still worth working through what it would mean.
At NZ$200 million of sales, a reasonable estimate of normalised EBITDA is NZ$40 to 65 million, with a central case near NZ$50 million, or a margin of about 20% to 30%. The arithmetic starts from a blended gross margin still in the mid 80s, which would put gross profit at about NZ$170 to 174 million. Operating costs should not double with sales. FY26 already showed leverage, and after the FY27 step up, commissions and some clinical costs stay variable while the sales force and overhead should scale more slowly.
The low end of that range assumes continued heavy commercial investment. The high end assumes better sales productivity and a richer Myriad mix. Aroa has not published an EBITDA target at NZ$200 million of revenue, so this is a scenario, not a forecast from the company.
If Aroa were delivering that earnings base and still growing at a solid double digit rate, a mid teens to low 20s EBITDA multiple would be the plausible market range, centred around 15 to 18 times. On NZ$40 to 65 million of EBITDA, that implies an enterprise value of roughly NZ$500 million to NZ$1.2 billion, before net cash.
Using about 346 million shares on issue, a New Zealand dollar around 90 Australian cents, and only today’s modest net cash, that equity value works out at roughly A$1.40 to A$3.20 a share. A central 15 to 18 times on NZ$50 million of EBITDA gives about A$2.00 to A$2.40.
The stock recently traded around A$0.57, a market value of roughly A$200 million. So the scenario implies a large re-rating rather than a small one, and it assumes little further dilution. The high end needs Myriad and Symphony still growing well and margins moving toward 25% to 30%. The low end fits if growth has slowed to high single digits or the market continues to treat Aroa as a niche wound care name.
Symphony: a disrupted market, and now the evidence
Symphony is the main external tailwind beyond Myriad’s scale up, and the timing has improved markedly this year.
From 1 January 2026, US Medicare set a single flat outpatient rate for most skin substitutes of US$127.14 per square centimetre. For years, outpatient skin substitute pricing had been something of a free for all, with Medicare spending on these products ballooning. The flat rate is expected to push high priced products and costly distribution models out of the market, and to shift more treatment into hospital outpatient departments, where Aroa already has inpatient accounts. A product that was built to be responsibly priced suddenly has a much fairer contest.
In July 2026, CMS proposed keeping that framework, including the same rate, for calendar 2027. That reduces the risk of another abrupt reset. Payers, meanwhile, are increasingly asking for randomised data before they cover advanced wound products routinely.
That evidence arrived on 5 October 2026. A 143 patient randomised trial published in the International Wound Journal found that adding Symphony to standard care closed 55% of Wagner grade 1 and 2 diabetic foot ulcers within 12 weeks, compared with 35% for standard care alone, and cut mean time to closure by 7.8 days, to 65.4 days. The improvement was statistically significant. The lead investigator was Dr David Armstrong, one of the best known names in diabetic foot research, which matters when sales teams sit down with hospital formulary committees.
Symphony is not yet a meaningful revenue line, and coverage decisions still have to follow the data. The tailwind is the combination of a disrupted, price capped market, a product already cleared and sensibly priced, and a published randomised result in a wound that too often ends in amputation.
What could go wrong
A thesis like this needs its risks stated plainly, and there are several.
TELA Bio is a real counterparty risk. OviTex revenue through TELA Bio was NZ$42.8 million in FY26, around 41% of group revenue. TELA’s own business has weakened. In its June quarter, TELA’s revenue fell 4% to US$19.3 million, OviTex PRS unit volumes fell 23%, its net loss widened and new chief executive Heather Getz withdrew full year 2026 guidance while she reassesses strategy. TELA reported cash of US$30.4 million at the time. Aroa’s FY27 guidance already assumes flat TELA sales, but a further deterioration, a restructuring at TELA, or any disruption to that relationship would hit both revenue and the cash flow funding Aroa’s own growth.
FY27 earnings will go backwards before they go forwards. Guidance of NZ$8 to 11 million of normalised EBITDA is below FY26’s NZ$12.6 million. If the new sales investment takes longer to become productive, the market may lose patience well before the leverage shows up. Bell Potter, which covers the stock, trimmed its EBITDA forecasts after the result while leaving revenue expectations broadly intact, which captures the tension well.
Symphony could be slower than hoped. A published trial does not equal coverage, and coverage does not equal sales. Outpatient wound care is crowded, hospitals are slow to change formularies, and Medicare policy in this area has changed sharply twice in two years. A third change is not impossible.
Currency and concentration. Aroa earns mostly in US dollars and reports in New Zealand dollars, so movements in the NZD/USD rate flow straight through reported revenue and margins. The business is also heavily exposed to the US hospital system and US reimbursement settings.
The valuation upside is a scenario, not a promise. It depends on management’s NZ$200 million ambition being met, on margins expanding, and on the market being willing to pay a growth multiple. Any one of those falling short would leave the outcome much closer to the low end, or below it. Further dilution, whether through employee options or a capital raise, would also reduce per share value.
Insider selling. Director John Diddams sold 200,000 shares on market at around A$0.63 on 26 June 2026. It is a modest sale relative to his remaining holding, but it is worth noting, and investors should form their own view.
What should long term investors actually do?
For long term investors, the practical question is not whether Aroa’s FY27 EBITDA line will be higher than FY26. It will not, and management has said so. The question is whether the company is spending its own cash on a channel that has already proven it can grow, and whether the next product has the evidence and pricing position to become a second engine.
On both counts the early evidence is encouraging. The half year result, due on 24 November 2026, will be the first real read on whether the new Myriad sales investment is translating into accelerating direct sales, and on how quickly Symphony is getting into hospital outpatient departments now that the trial is published.
This is a small, illiquid stock with genuine counterparty and execution risk. It is not suited to every portfolio, and position sizing matters. But the market appears to be pricing Aroa as a niche New Zealand wound care company with a struggling distributor, rather than as a profitable, founder led, cash funded device business with a high margin growth product and a newly validated launch.
TAMIM Takeaway
ARX is a founder led, industry leading, cashed up, growing and profitable business, with catalysts and a cheap valuation.
Brian Ward founded the business and still runs it. Myriad is the growth leader inside a high margin soft tissue niche, with OviTex providing partner revenue at no sales force cost. The balance sheet is debt free with NZ$27.1 million of cash, and the company is already growing and profitable on a normalised EBITDA basis, even while it reinvests.
The catalysts are the Myriad sales ramp, the reset in US outpatient skin substitute reimbursement, and the newly published diabetic foot trial for Symphony. The key risk to watch is TELA Bio. At around A$0.57, against a scenario value of roughly A$1.40 to A$3.20 if sales reach NZ$200 million, the entry is cheap relative to that outcome, provided the growth and the multiple both arrive. We think the risk reward is highly attractive.
_______________________________________________________________________________________
General advice warning: This article contains general information only and does not take into account your objectives, financial situation or needs. Past performance is not a reliable indicator of future performance. Scenario valuations are illustrative and are not forecasts. Before making any investment decision, consider whether the information is appropriate for your circumstances and seek professional advice if needed.
Disclaimer: Aroa Biosurgery Limited (ASX: ARX) is held in TAMIM portfolios as at the date of article publication. Holdings can change substantially at any time.