Australian Equities
Australia Small Cap Income
Investor updates
Below you will find this month’s commentary and portfolio update for TAMIM Australia Small Cap unit class.
October 2026 | Investor Update
Dear Investor,
We provide this monthly report to you following conclusion of the month of October 2026.
The TAMIM Small Cap Income Fund was down – 3.03% (net of fees) during the month, versus the Small Ords down – 6.43%. Emerging Companies (XEC) dropped a whopping -9.32%.
Smaller stocks suffered as the RBA continued hiking rates to combat sticky inflation, fuelled by elevated oil prices from Middle East tensions. Higher borrowing costs and risk aversion hit rate-sensitive growth names hardest, amplified by uncertainty ahead of US midterm elections.
By contrast, the ASX200 held up thanks to strength in the big banks (Financials sector +7%), which benefited from wider net interest margins in a higher-rate environment and investor preference for defensive large-caps and continuous flows from passive index funds into the largest stocks.
The month also saw an aggressive sentiment shift towards AI stocks and neo-clouds. It started from the overhyped but ultimately withdrawn IPO of Firmus, and cascaded to other global neo-clouds and their prospects of securing funds. Having taken profits and sold our positions in the sector earlier, our lack of exposure benefited us during the month.
As we look ahead into November, sentiment is beginning to improve towards small caps and growth companies. Following a sweeping win for the Democrats in the US midterms, political gridlock is a familiar setup. Markets have tended to respond well to this backdrop as it reduces policy uncertainty.
The prospect of a divided government could ultimately provide a more supportive backdrop for equities by limiting major policy changes and reducing uncertainty around fiscal spending. With control of Congress and the White House split, sweeping legislative change is less likely.
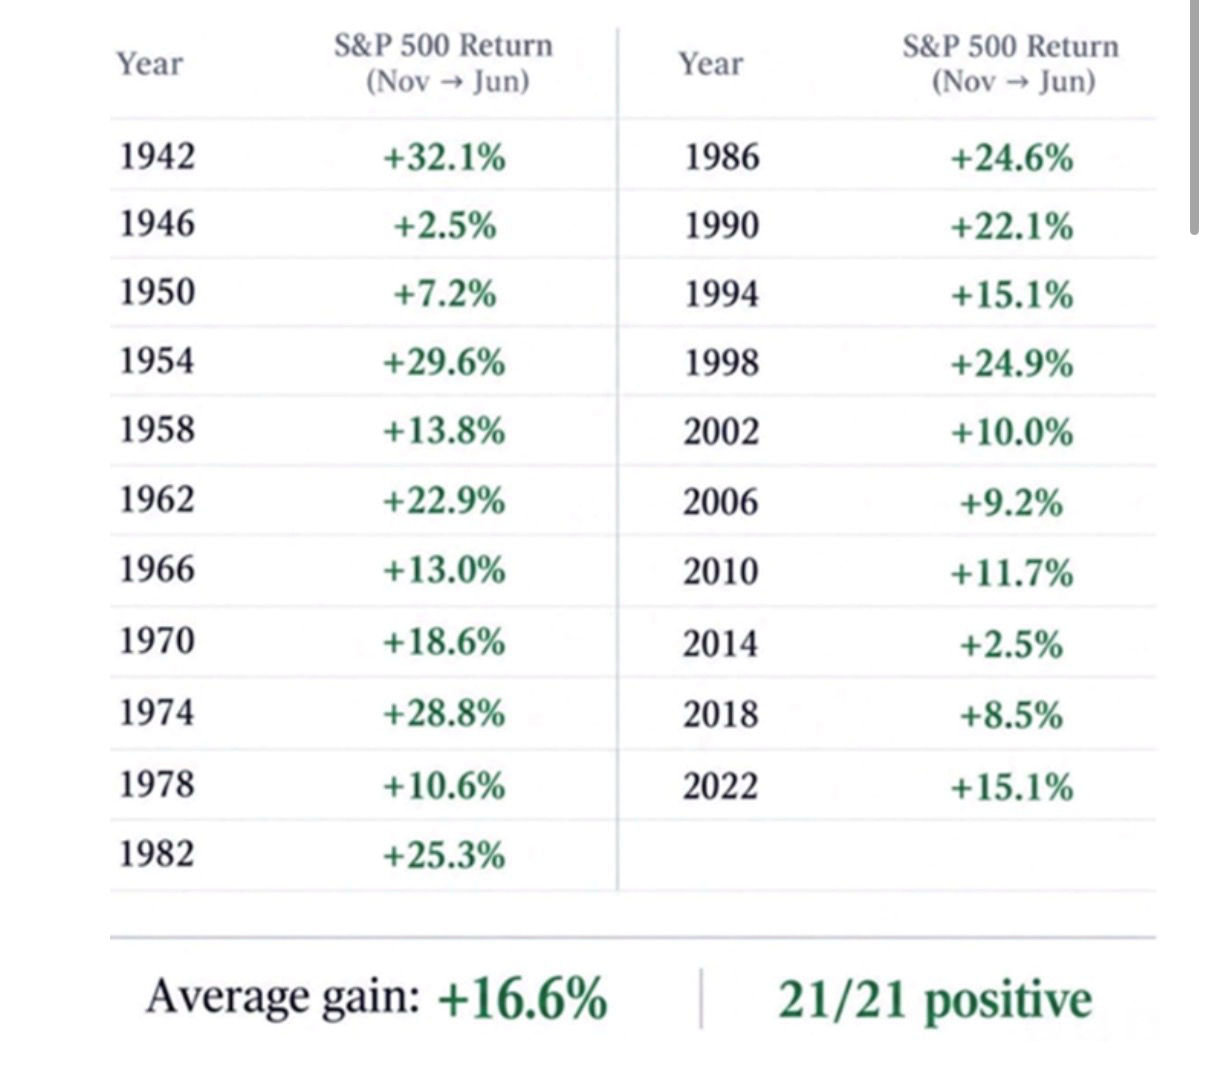
In addition, US–Iran peace talks are progressing and WTI crude is back to around US$85 (down about 20% in a week in early November). Markets have tended to do well after midterms, with the S&P 500 up an average of 16.6% from November to June after every midterm since 1942 (21 of 21 positive).
Finally we provide a brief commentary on portfolio updates during the month in the portfolio section of the report. We look forward to providing further updates in our next monthly report in December.
Sincerely yours,
Ron Shamgar and the TAMIM Team.
Fund Performance
Portfolio Highlights

Baby Bunting (ASX: BBN) AGM update showed the Store of the Future programme continuing to deliver. Year-to-date underlying comparable sales were up 2.2% (Australia +2.0%, New Zealand +8.7%), with the recent moderation reflecting temporary store closures for refurbishment. The 17 refurbished stores now trading are generating cumulative average sales growth of 20%.
Management reaffirmed FY27 guidance for pro-forma NPAT of $19–21 million on total sales of $585–600 million, comparable sales growth of 3–5% and a gross margin of 42%. Capital expenditure of $33–37 million is expected to be fully funded from operating cash flow. With a further 10–12 refurbishments and three new large-format stores planned, the company remains on track to restore longer-term EBITDA margins above 10%. BBN trades on a PE of 8x whilst being the clear market leader in what is generally a defensive retail category. Historically the stock has traded on high double digit multiples and we believe once the rate hike cycle has ended the stock will re-rate higher.
EDU Holdings (ASX: EDU) reported strong enrolment growth for Trimester 3. Group total enrolments rose 26% to a record 7,489, driven by Higher Education (Ikon) which grew 45% to 6,571 and now accounts for 88% of the group. Domestic Higher Education new-student numbers jumped 78% and the postgraduate mix doubled to 28%. New enrolments overall were softer, down 13%, reflecting weaker vocational intake and the impact of recent student-visa rule changes on international students.
The company also renewed its on-market buy-back for a further 12 months. While no formal earnings guidance was issued, the sustained expansion of the higher-education book continues to underpin the growth story. The stock was sold off during the month. In the meantime, directors have been buying shares and the stock is trading on a PE of about 9x and a dividend yield of about 7%.
Motorcycle Holdings (ASX: MTO) At its Investor Day outlined the next phase of its evolution from Australia’s largest motorcycle retailer into a broader powersports platform. The strategy encompasses motorcycles, ATVs, side-by-sides, personal watercraft, parts, accessories, apparel, servicing and finance/insurance, supported by three interconnected segments. FY26 already demonstrated the model’s momentum, with revenue of $789 million, underlying NPAT of $25.7 million and EPS of 34.8 cents.
Wholesale remains a high-return engine, contributing roughly one-third of revenue but the bulk of segment profit, underpinned by exclusive distribution rights (including CFMOTO). Management’s focus is on scaling the platform through acquisitions, new suppliers and digital transformation while continuing to optimise the retail network. MTO set five-year ambitions to FY31 with Wholesale revenue of more than $400 million, with a PBT margin of 12.5–13.5%. And Retail revenue of more than $800 million, with a PBT margin of 2–3%.
Praemium (ASX: PPS) AGM and Q1 update confirmed continued growth in funds under administration. Platform FUA rose 7.4% year-on-year to $34.4 billion, supported by positive net flows of $274 million in the September quarter. Scope+ non-custodial FUA grew more strongly, up 30% to $45.5 billion. In FY26 the business delivered revenue of $110.5 million (+5.7%) and underlying EBITDA of $32.1 million (+14.5%).
Looking ahead, management is shifting reporting and incentive frameworks toward cash EBITDA (EBITDA less capitalised development) and targeting improved cash conversion. With Spectrum continuing to win advisers and the platform technology transformation under way, Praemium remains well positioned to benefit from the structural shift toward managed accounts. We believe the new CEO and Chair are simplifying the business and making it more attractive for an acquirer. On 8x EBITDA the stock is cheap.
Fund Facts
Investment Parameters
| Management Style: | Active |
| Investments: | Australian Equities |
| Investment Universe: | Australian Small Cap |
| Reference Index: | ASX Small Ords |
| Number of Securities: | 20-40 (10-20 Value, 10-20 Growth) |
| Single Security Limit: | +/-5% |
| Market Capitalisation: | Small Cap |
| Leverage: | No |
| Portfolio Turnover: | <50% p.a. |
| Cash Level (typical): | 0-100% (0-50%) |
Fund Profile
| Investment Structure: | Unlisted Unit Trust (available to wholesale investors) |
| Minimum Investment: | $100,000 |
| Management Fee: | 1.25% p.a. |
| Admin & Expense Recovery: | Up to 0.35% |
| Performance Fee: | 20% of performance in excess of hurdle |
| Hurdle: | Greater of: RBA Cash Rate + 2.50% or 4% |
| Entry/Exit Fee: | Nil |
| Buy/Sell Spread: | +0.25% / -0.25% |
| Distributions: | Semi-annual |
| Applications/Redemptions: | Monthly |
| Redemptions: | Monthly with 30 days' notice |
| Investment Horizon: | 3 - 5 years + |
Invest via TAMIM Fund
Request additional details by using the form or if you're ready to invest select the apply now button.
Invest via IMA
The TAMIM Australia Small Cap strategy is available as an Individually Managed Account (IMA). Please see the Strategy Summary for terms or request Investment Documentation via form.